Top 6 Lenders for Long-Term Personal Loans in 2026
Last updated: 2026-10-17
Hunting for a lender that supports a twelve-year repayment window is a bit like looking for a needle in a haystack. Most standard personal loans stop their clocks at seven years, leaving anyone needing long-term flexibility in a tight spot. If you want to spread out payments to keep your monthly costs manageable, you have to look beyond «quick cash» providers.
You will likely need an institution that understands long-term debt restructuring or large-scale asset financing. Selecting the right partner involves more than just glancing at a single interest rate. You have to weigh how fast you get the money against the total interest you will pay over a decade.
A loan with a lower monthly payment over 144 months might look attractive on paper. However, once you run the math, you might find you are paying nearly double the principal in interest alone. This list looks at the top contenders to help you manage the complexities of long-term borrowing without falling into a debt trap.
U.S. Bank
Wells Fargo
JetzLoan
Citi
OneMain Financial
Alliant Credit Union
How These Lenders Were Evaluated
The evaluation process focused on availability, flexibility, and the ability to handle extended durations. Since most traditional banks cap terms at 84 months, the search prioritized lenders known for versatility. We examined how these companies handle the application process and the speed at which they distribute cash. We also looked at their reputation regarding transparency in fee structures.
We specifically looked for lenders that do not penalize borrowers for making extra payments. This is the most effective way to mitigate the long-term interest costs associated with extended repayment windows. Reliability and accessibility were the other major pillars of this comparison. A lender might offer a great rate, but if they require a mountain of paperwork or a week of waiting, they lose points.
We looked for a balance between institutional stability and modern, digital-first convenience to ensure a well-rounded list for various borrower needs. We also accounted for «hidden» variables, such as the difference between APR (Annual Percentage Rate) and the base interest rate. This ensures that recommendations prioritize the actual cost of borrowing.
Lender
Max Loan Amount
Term Range
Funding Speed
Credit Check Type
U.S. Bank
see site
see site
see site
see site
Wells Fargo
$100,000
12-84 months
see site
see site
JetzLoan
$50,000
see site
24 hours
No hard pull
Citi
$30,000
12-60 months
see site
see site
OneMain Financial
$30,000
24-60 months
1 hour
see site
Alliant Credit Union
see site
see site
see site
see site
The Best Long-Term Personal Loan Options
1. U.S. Bank
This institution remains a titan in the banking world, offering a comprehensive suite of services. For those seeking a personal loan, they provide a structured environment where you can manage your checking, savings, and loans all under one roof. It is a powerhouse for those who prefer a traditional banking relationship.
Their interface is designed for high-net-worth individuals and long-term planners who value the cohesion of a single institution. The loan products are designed for stability, which is essential when you are looking at long-term debt. If you already have a relationship with a large bank, the convenience of having everything in one dashboard can be a massive advantage for your monthly budgeting.
For instance, setting up an automatic transfer from your checking account to cover your loan payment is simple. This reduces the risk of accidental late fees, which can be devastating over a decade-long term. It is a solid choice for someone who wants everything in one place.
Pros:
Integrated banking ecosystem for easy management.
Wide variety of financial products including investing.
Established institutional reputation.
Cons:
May require more documentation than digital-only lenders.
2. Wells Fargo
Wells Fargo is a heavy hitter when it comes to high-limit personal loans. If you are looking to tackle a major life event, such as a home renovation or a significant debt consolidation, their ability to provide up to $100,000 is hard to ignore. They offer a very competitive starting rate to attract serious borrowers, particularly those with established credit histories.
This makes them a primary choice for large-scale projects that require significant capital upfront. The predictability of their fixed interest rates is a lifesaver for anyone planning their finances years in advance. You won’t have to wake up one morning to find your monthly payment has spiked due to market volatility.
This provides a sense of security that is vital for long-term planning. When comparing them to variable-rate lenders, the «peace of mind» factor of a fixed rate often outweighs the slightly higher initial rate offered by more aggressive, risk-prone lenders. It is about knowing exactly what you owe every single month.
Pros:
High maximum loan amounts up to $100,000.
Fixed interest rates provide long-term predictability.
Extensive branch network for in-person support.
Cons:
High loan amounts may require excellent credit.
3. JetzLoan
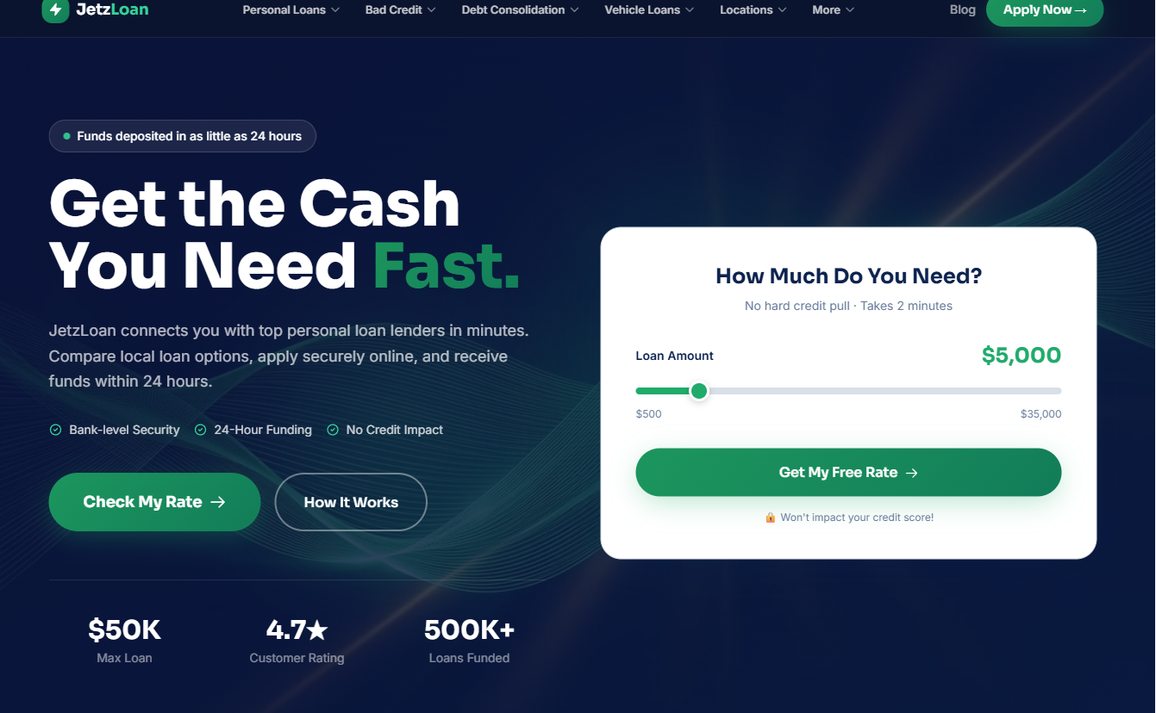
Speed is the name of the game here. If you find yourself in a position where you need cash yesterday, JetzLoan is built for that exact moment. They focus on getting funds into your account in as little as 24 hours, making them a lightning-fast option for urgent needs.
This is ideal for emergency repairs, medical bills, or immediate business opportunities where the cost of waiting is higher than the cost of a slightly higher interest rate. One of the most refreshing aspects of their process is the ability to check your rate without a hard credit pull. This allows you to shop around without risking a dip in your credit score.
This «soft pull» mechanism ensures that you can perform a cost-benefit analysis of different lenders before making a final commitment that will impact your credit profile. It takes the guesswork out of the initial stages of borrowing. You get the facts without the damage to your score.
Pros:
Extremely fast funding, often within 24 hours.
No hard credit pull to check rates.
High customer rating for their streamlined process.
Cons:
Maximum loan amount is capped at $50,000.
4. Citi
Citi offers a polished, digital-first experience that caters to the modern consumer. Their personal loans are ideal for those who want a streamlined application process. With repayment terms spanning up to 60 months, they provide a solid middle ground for many mid-term financial goals.
Their mobile app is frequently cited as a benchmark for user experience. This allows for easy tracking of principal reduction and interest paid. They are particularly well-suited for people who want to manage their finances through a sophisticated online interface. While they may not offer the extreme twelve-year stretches found in some niche markets, their structure is incredibly efficient.
If your goal is to consolidate high-interest credit card debt into a more manageable 5-year plan, Citi is a top-tier candidate. It is a great option for someone who wants a smooth, digital experience without needing a decade-long commitment. Their interface makes the math very easy to see.
Pros:
Excellent digital banking and online interface.
Well-structured repayment terms up to 60 months.
Strong reputation for managing high-limit credit.
Cons:
Maximum term is 60 months, not 12 years.
5. OneMain Financial
If you feel like the big banks have turned their noses up at you, OneMain Financial might be your best bet. They specialize in providing options to people who might have a less-than-perfect credit history. Their ability to get you money as soon as one hour after signing is legendary.
They focus on the individual’s current ability to repay rather than just a static credit score, making them a vital resource for those in transition. They lean heavily into the human element of banking, with a massive network of over 1,300 branches. This means that if you run into a snag, you can actually walk into a building and talk to a real person.
This is much better than shouting at a chatbot when things get complicated. This physical presence provides a layer of accountability and support that digital-only fintechs simply cannot replicate, especially when navigating complex loan terms. It offers a sense of stability when you are in a tough spot.
Pros:
Extremely fast funding, potentially in one hour.
Large physical presence with 1,300+ branches.
Accessible for those with non-standard credit.
Cons:
Interest rates can be higher for some borrowers.
6. Alliant Credit Union
Credit unions often offer a different flavor of banking, and Alliant is no exception. Because they are member-owned, their focus often shifts toward providing better rates and more benefits to their members. Their high-rate savings and checking accounts make them a great place to park your money.
This member-centric model often results in lower fees compared to the «Big Four» national banks. While they are a powerhouse for savings and certificates, their loan products are part of a broader ecosystem. They are an excellent choice for those who want their money to work harder through higher interest yields.
For a borrower looking to build long-term wealth while managing existing debt, the Alliant ecosystem provides a holistic approach to personal finance. It is a smart play for those who want to stay within a community-focused financial environment. You get quality credit products alongside strong savings tools.
Pros:
Member-owned structure often leads to better rates.
High-yield savings and checking options.
Excellent digital banking improvements.
Cons:
Membership requirements may apply.
The Hidden Costs of Long-Term Debt
When you extend a loan to its maximum duration, you are essentially trading monthly cash flow for total interest expense. It is vital to understand the math behind this trade-off. For example, consider a $20,000 loan. At a 10% interest rate, a 5-year term results in roughly $5,500 in total interest.
However, if you stretch that same $20,000 out to 10 years, even at the same 10% rate, you will pay approximately $11,700 in interest. You have doubled your monthly comfort but more than doubled your total cost. Understanding the «Effective Cost of Borrowing» is essential to avoid being blindsided by the numbers later on.
This includes several specific factors to watch for:
Origination Fees: Some lenders charge a percentage of the total loan (often 1-8%) just for processing the application. This is taken out of your initial funds, meaning you receive less than the amount you actually owe.
Prepayment Penalties: Many long-term loans include clauses that charge you a fee if you pay the loan off early. This is because the lender loses out on the interest they expected to collect from you. Always prioritize lenders that allow «penalty-free» early repayment.
Late Fees and Compounding Interest: In a 12-year term, a single missed payment or a short delay can trigger compounding interest. You end up paying interest on your interest. This can cause the principal to stagnate or even grow.
How to Navigate Long-Term Borrowing
Before you sign on the dotted line, you must realize that a twelve-year loan is a massive commitment. While the monthly payments might look tiny, the total interest you pay over a decade can be staggering. It is like a marathon; you need to ensure you have the stamina to keep running for the full duration.
Your income, career stability, and cost of living will all change over twelve years, and you must plan for that volatility. Avoid the temptation to take the longest term just because you can. A longer term reduces your immediate monthly burden, but it increases the total cost of the loan significantly. If you can afford to pay more each month, you will save thousands of dollars in the long run.
A common strategy is to take the long term to ensure you can always meet the minimum payment, but to aggressively pay extra whenever you receive a bonus, tax refund, or raise. This gives you the «safety net» of a low monthly requirement with the «wealth-building» benefit of a short-term loan. It is about having flexibility when things are tight and speed when you have extra cash.
Watch out for hidden fees that can sneak into the contract. Always ask about prepayment penalties. If you come into some extra cash and want to pay off the loan early, you don’t want the bank to punish you for being responsible. Always read the fine print before you let anyone access your bank account.
Specifically, look for the phrase «all payments are applied first to interest and then to principal»—this is standard, but you want to ensure you can make extra payments that go directly toward the principal balance. This is the fastest way to accelerate your path to debt freedom and stop the interest from eating your income.
Dreaming of a tropical escape or a mountain retreat can feel like a distant fantasy when your bank account is looking thin. Sometimes, life happens. Credit scores take a hit, making traditional financing feel like a closed door. Whether it is a sudden medical expense, a period of unemployment, or simply a gap in your savings, financial setbacks are common. They do not have to mean the end of your travel aspirations.
Travelers often find that specialized lenders are willing to look beyond a single number to see your true potential as a borrower. When searching for a way to fund your next journey, the primary goal is finding a balance between accessibility and cost. You want a lender that understands your situation without trapping you in a cycle of high-interest debt. It is a delicate dance between immediate gratification and long-term stability.
For example, a traveler might be tempted by a quick «payday» style loan to cover an immediate flight booking, but the astronomical interest rates can lead to a debt spiral. This can prevent any future travel for years. Instead, the goal should be finding structured, predictable financing that fits your post-vacation budget. This ranking examines the top options available for those needing a little extra help to reach paradise.
FastLendGo
Discover
60MonthLoans
LightStream
LoanStart
How These Lenders Were Evaluated
The selection process focused on how accessible these lenders are for individuals with less-than-perfect credit histories. We looked at the range of loan amounts available and how quickly a person could actually get their hands on the cash. After all, a flight deal won’t wait if you are stuck waiting weeks for a decision. By the time the funds hit your account, the price of the hotel might have doubled.
We also prioritized lenders that offer soft credit inquiries for pre-qualification. This allows you to shop around without worrying about your score dropping further due to multiple «hard pulls» from different institutions. You can check your options without the fear of damaging your credit profile during the research phase.
We analyzed several key metrics for each provider:
Approval Accessibility: How likely are they to approve someone with a score in the 580-640 range?
Speed of Disbursement: Can the funds be used for a last-minute booking, or is the process bogged down in manual verification?
Transparency: Does the lender clearly state their interest rates and fee structures upfront?
Loan Versatility: Can the funds be used for anything from a cruise deposit to an international train pass?
The goal was to identify services that provide genuine options for travelers who need flexibility and speed to secure their dream getaway.
Lender
Loan Amounts
Credit Requirements
Funding Speed
FastLendGo
$500 – $5,000
Bad/Fair Credit
See site
Discover
Up to $40,000
See site
60MonthLoans
$2,600 – $10,000
See site
LightStream
See site
Excellent Credit
LoanStart
Up to $40,000
See site
Top Rated Lenders for Your Next Getaway
1. FastLendGo
FastLendGo is a lifeline for those who might be struggling to find traditional banking support. They specialize in various personal financing solutions, including options specifically designed for those with bad or fair credit. It is a versatile choice for anyone needing a quick injection of cash for emergencies or small travel needs. If you have found a flash sale on a boutique hotel in Mexico and only need $800 to lock in the rate, FastLendGo is structured to handle those smaller, high-velocity transactions.
This lender is particularly useful for smaller, immediate requests. Whether you need a few hundred dollars for a weekend getaway or a few thousand for a domestic road trip, their structure accommodates different scales of spending. It is a practical option for someone who needs to move quickly without the heavy scrutiny of a major bank. Unlike large banks that might require extensive documentation for a $500 loan, these lenders are built for speed and accessibility.
Pros:
Specializes in bad and fair credit options.
Offers small personal loans starting at $500.
Covers a wide range of states.
Cons:
Loan amounts are relatively low compared to others.
2. Discover
Discover is a heavyweight in the financial world, offering a sense of stability that many niche lenders lack. They provide personal loans that can be used to finance significant travel expenses, including cruises and flights. It is a solid option for those who want to integrate their travel funding with a well-known brand. Because Discover is a major institution, their interface is highly intuitive, making it easy to manage your repayment schedule through their mobile app.
The ability to finance up to $40,000 makes this a serious contender for major life experiences, such as a honeymoon in the Maldives or a multi-stop tour through Europe. They offer a streamlined application process that allows you to check for pre-approval without impacting your credit score. This is a massive advantage when you are trying to gauge your options carefully without risking your eligibility for other credit products like car loans or mortgages.
Pros:
Large loan amounts up to $40,000.
Pre-approval does not affect credit score.
Widely accepted and highly reputable.
Cons:
May have stricter requirements for the highest loan amounts.
3. 60MonthLoans
If you are looking for a more structured repayment plan, 60MonthLoans offers a straightforward approach. They provide personal loans ranging from $2,600 to $10,000 with terms that can stretch up to five years. This can make monthly payments much more manageable for a budget-conscious traveler. For instance, if you are financing a $5,000 trip, spreading that cost over 36 to 60 months prevents the «post-vacation hangover» where you feel broke for months after returning home.
The application process is designed for the modern, mobile-first user, taking only about ten minutes to complete. Once a decision is made, funding can happen as quickly as one business day. This speed is essential for travelers who need to secure a reservation before a price hike occurs. It is a solid choice for someone who wants a balance of speed and predictable long-term terms.
Pros:
Terms up to 5 years for flexibility.
Fast decision-making process.
No collateral required for applicants.
Cons:
Lower maximum loan amount compared to major banks.
4. LightStream
LightStream is the premium option on this list, catering to those with a very strong financial standing. They offer low fixed rates, particularly if you opt for AutoPay, which can save you money over the life of the loan. For a high-income professional planning a luxury safari, LightStream offers the most cost-effective way to borrow capital without the high interest rates associated with credit cards.
The service is known for being incredibly smooth and quick, with some users reporting funds in their accounts the very next day. If you have worked hard to maintain excellent credit, this lender provides some of the most competitive rates available for your travel needs. They are ideal for those who want to borrow large sums for major life events without the burden of excessive interest.
Pros:
Very competitive low fixed rates.
Extremely fast funding turnaround.
User-friendly digital application.
Cons:
Requires excellent credit to access best rates.
Rates are higher if you do not use AutoPay.
5. LoanStart
LoanStart functions as a gateway to a network of reliable affiliate lenders. Instead of just one set of rules, they attempt to pair you with a partner that fits your specific profile. This can be a lifesaver if you have been rejected by traditional banks or credit unions. For example, if your income is variable, such as freelance work or seasonal employment, LoanStart’s network might include a lender more comfortable with non-standard income streams.
They offer the potential to borrow as much as $40,000, making it a high-capacity option for significant adventures. Because their service is free to use and doesn’t affect your credit score during the initial phase, it is a low-risk way to see what you qualify for. It essentially acts as a specialized matchmaker for your financial needs.
Pros:
Access to a wide network of lending partners.
High borrowing potential up to $40,000.
Free service with no initial credit impact.
Cons:
You are being paired with an affiliate, not borrowing directly.
Real Costs of Travel Loans
While securing funds for a trip is exciting, it is essential to understand the mechanics of interest. When you take out a personal loan for travel, you are essentially paying for the privilege of experiencing your destination today rather than later. This «convenience fee» is the interest you pay over the life of the loan.
Consider these two common scenarios:
Scenario A: The Credit Card Route: Many travelers use a standard credit card for a $3,000 vacation. If they only pay the minimum amount each month and the APR is 22%, they could end up paying back nearly double the cost of the trip over several years.
Scenario B: The Structured Personal Loan: Using a lender like 60MonthLoans for that same $3,000 trip with a 12% APR over 3 years results in a much more predictable monthly payment and significantly less total interest paid.
By choosing a structured loan over revolving credit card debt, you gain control over your timeline and total cost, making your travel more sustainable in the long run.
How to Prepare Your Application for Approval
If you are concerned about your credit score, you can still improve your chances of approval by being meticulously prepared. Lenders look for stability and reliability. Even if your score isn’t perfect, showing that you have a steady stream of income and a clear plan for repayment can make a significant difference.
Follow these steps to increase your chances of a successful application:
Verify Your Income: Have your last three months of pay stubs or tax returns ready. Lenders want to see that your current income can comfortably support the new monthly payment.
Review Your Debt-to-Income (DTI) Ratio: Before applying, calculate your total monthly debt payments divided by your gross monthly income. If this number is too high, consider paying down a small credit card balance before applying for the loan.
Check for Errors: Disputes on your credit report regarding outdated late payments can tank your score. Use a free service to ensure your report is accurate before a lender sees it.
Be Honest About Your Needs: Don’t over-borrow. If you only need $2,500 for your flights and hotels, don’t ask for $5,000. A lower loan amount is easier for a lender to approve and keeps your interest costs down.
Avoiding Common Lending Pitfalls
Before you sign on the dotted line, it is vital to remember that all debt is a commitment. Even if you are excited about a beach in Bali, a high-interest loan can quickly turn a dream into a nightmare. Always read the fine print regarding late fees and how interest is calculated. Some loans use «simple interest,» while others may use more complex methods that increase your total cost if you pay the loan off early.
Avoid the temptation to take out more money than you can realistically pay back every month. It is often better to wait a few more months to save up a larger down payment than to borrow heavily and struggle to make payments. A vacation should be a way to de-stress, not a source of financial anxiety. If you find yourself struggling to make payments, contact your lender immediately; many have hardship programs that can help you restructure your loan before it impacts your credit score further.
Trying to fix your finances when your credit score is in the gutter feels like walking through a thunderstorm without an umbrella. You need cash quickly, but traditional banks often slam the door before you even reach the lobby. Today, searching for digital signatures and quick approvals is the most efficient way to find relief.
When a mountain of medical bills arrives or a car repair suddenly breaks the bank, you don’t have the luxury of waiting weeks for a manual review. The digital age has changed the game, turning what used to be a week-long ordeal of paper shuffling into an experience you can finish from your smartphone while sitting on your couch.
This list highlights lenders that understand that urgency. When searching for electronic signing options, speed and accessibility are what matter most. We looked at how these companies handle various credit profiles to help you find a lifeline that actually works for your specific situation.
We didn’t just look at interest rates. We examined the friction points in their application processes, how clear their digital interfaces are, and the actual speed at which funds hit your bank account after you apply your electronic signature.
Lift Credit
OneMain Financial
JetzLoan
Avant
Upgrade
How These Digital Lenders Were Evaluated
Our selection process focused on accessibility and how easy it is to complete a digital application. Offering money is only half the battle; the process needs to be smooth from the first click to the final electronic signature. We sought out lenders that remove the hurdles common in traditional banking.
We investigated how many steps it takes before a user receives a definitive «yes» or «no.» We also looked at whether applications require scanning and uploading physical documents or if they use automated verification systems that pull your data instantly. This distinction makes a massive difference when you are in a hurry.
We prioritized companies that provide clear information regarding loan amounts and funding timelines. Speed matters when you are facing an emergency repair. A lender that promises «fast funding» but takes five business days to process the transfer is not a high-speed option for someone in a crisis.
The goal was to find providers that offer a legitimate path forward without hiding behind confusing jargon or impossible requirements. We scrutinized the fine print regarding how they treat people with «thin» credit files, specifically those who lack a long history but have a steady income stream.
Lender Name
Loan Amounts
Funding Speed
Credit Requirements
Terms
Lift Credit
see site
Same day
Regardless of credit
Installment
OneMain Financial
$1,500 – $30,000
As soon as 1 hour
See site
24-60 months
JetzLoan
$500 – $35,000
As little as 24 hours
No hard credit pull
see site
Avant
see site
see site
See site
see site
Upgrade
Up to $50,000
Fast funding
see site
Fixed rate
The Best Options for Quick Digital Funding
1. Lift Credit
Lift Credit serves residents in Utah, Idaho, Nevada, and Missouri. They offer installment loans that are often more affordable than the payday lenders that often target people with poor credit. Payday loans frequently use a «lump sum» repayment model, which can trap borrowers in a cycle of debt.
Lift Credit avoids that trap by using an installment model. You pay the money back in smaller, manageable chunks over a set period. This structure makes it much easier to keep your head above water while you work through your debt.
The application is built for speed, so you can apply online in just a few minutes. It is a great choice if you want a digital solution without a trip to a physical office. Keep your most recent pay stub and a valid ID ready to upload to ensure you actually get that same-day funding.
Pros:
Same-day funding available
Works regardless of credit standing
Simple, affordable repayment schedules
Cons:
Geographic restrictions apply
Not available for all US residents
2. OneMain Financial
OneMain Financial acts as a bridge between traditional banking and modern digital convenience. With 1,300 branches, they offer a human touch that online-only lenders often lack. This is helpful if you run into a technical glitch with a digital signature or if your income is non-traditional.
If you are a gig worker or have seasonal employment, being able to explain your situation to a real person is a massive advantage. They cater to a wide range of needs, providing loans that range from $1,500 up to $30,000.
You can see potential terms in about five minutes using their digital tools. This is perfect if you want to explore your options without any obligation or immediate impact on your credit score. They often take a more holistic view of your ability to repay rather than just looking at a single FICO score.
Pros:
Extensive branch network for support
Fast funding after loan signing
Wide variety of loan amounts
Cons:
Requires a loan signing process
May require visiting a branch for some services
3. JetzLoan
JetzLoan works as a high-speed connector in the lending marketplace. They specialize in moving you from an application to funded status in as little as 24 hours. Because they connect you with various top lenders, you get a broad search without the headache of filling out ten different forms.
Think of them as a specialized search engine for personal loans. Instead of you visiting every single website, JetzLoan does the heavy lifting of finding the lenders most likely to approve your specific profile.
One of their standout features is the ability to check your rate without a hard credit pull. This is a massive distinction. A «hard pull» stays on your report and can lower your score, while a «soft pull» is just a quick peek to see if you’re a match.
This allows you to scout for the best deal without bruising your credit score further. It is a low-risk way to see if you qualify for amounts up to $50,000 while you hunt for the best interest rate.
Pros:
No hard credit pull for rate checks
Very fast 24-hour funding window
High customer rating for transparency
Cons:
Connects to third-party lenders
Process depends on external lender speed
4. Avant
Avant positions itself as a partner in your financial journey rather than just a source of cash. They offer various tools, including credit cards and installment loans, to help people move through different life stages. Their focus is on providing flexible choices.
This is particularly useful if you are trying to «reset» your finances. You might use a single installment loan to consolidate several smaller, higher-interest debts into one manageable monthly payment. It is a way to simplify your life.
Whether you are dealing with an emergency or looking to consolidate debt, Avant provides specific solutions. Someone with a moderate credit score might find more success with their credit card products, while someone needing a large lump sum for a home repair might prefer their installment loans.
Pros:
Multiple financial products available
Focus on long-term financial goals
User-friendly digital tools
Cons:
May have stricter requirements for some products
Not a one-size-fits-all solution
5. Upgrade
Upgrade is a heavyweight in the personal loan space, serving over 8 million customers. They offer large loan amounts, reaching up to $50,000, with fixed rates that keep your monthly budget predictable. This is a strong choice for significant expenses like home improvement or medical procedures.
Because the rate is fixed, your monthly payment will never change. This provides a vital safeguard against inflation or sudden shifts in your spending needs. You won’t wake up to a surprise increase in your interest rate.
The platform is highly integrated, offering everything from personal loans to rewards checking accounts. You can check your rate for free to see exactly where you stand before committing to any debt. This «no-obligation» check lets you compare potential payments against your income before you ever provide a digital signature.
Pros:
Large loan amounts available
Fixed rates for predictable payments
Extensive range of financial products
Cons:
May not be the cheapest for top-tier credit
Complex ecosystem may be overwhelming for some
Comparing Loan Types: Personal vs. Payday
When you are in a rush, it is easy to take whatever is offered. However, understanding the difference between a personal installment loan and a payday loan is critical. A personal loan is a structured agreement with a set end date and a capped interest rate.
A payday loan is often a short-term «bridge» that is incredibly difficult to pay back. The interest rates can effectively reach 400% or higher when calculated annually. These are the kinds of loans that lead to a downward spiral.
Feature
Personal Installment Loan
Payday/Short-Term Loan
Repayment Period
Months to Years
Usually 2-4 Weeks
Interest Rate (APR)
Moderate (Fixed or Variable)
Extremely High
Credit Impact
Can build credit if paid on time
Often no benefit; can harm credit if defaulted
Total Cost of Borrowing
Predictable and manageable
Can lead to a cycle of debt
If you can find a lender from our list that offers a personal loan, you are almost always in a better position than if you turn to a local check-cashing store. Even if the interest rate seems high compared to a mortgage, it is much lower than predatory alternatives.
How to Choose Your Next Loan
Selecting the right lender is like picking a pair of shoes; it has to fit your specific situation perfectly. If you need money by the end of the day, look at the funding speed first. If you are worried about your credit score, prioritize lenders that offer soft credit pulls for rate checking.
If you have a complex financial history, you might want to opt for a lender with a physical presence, such as OneMain Financial. Having a person you can speak with to clarify your income details can prevent many headaches later on.
Avoid the trap of only looking at the monthly payment. A low monthly payment often means a much longer term, which results in you paying significantly more in interest over the life of the loan. A $5,000 loan with a $100 monthly payment might seem easy, but if it stretches over 72 months, you are paying back nearly double what you borrowed.
Always read the fine print regarding late fees and prepayment penalties. Some lenders will punish you for being responsible and paying the loan off early. Look for flexibility and a «no prepayment penalty» clause. This allows you to improve your financial standing without being penalized for your own success.
6 Best Lenders for Plastic Surgery Loans for Bad Credit in 2026
Last updated: 2026-10-16
Walking into a surgeon’s office should feel like a step toward a new you, not a descent into financial dread. Many people find themselves staring at a dream procedure while their credit score sits in the basement, making the dream feel entirely out of reach. It is a heavy burden to carry when your physical goals collide with your financial reality.
The psychological weight of debt can often overshadow the excitement of a transformation. This creates a cycle of anxiety that prevents many from seeking the care they need. It is hard to focus on healing when you are worried about how to pay for the scalpel.
Finding the right way to pay for cosmetic work requires looking past the shiny brochures. You need a lender that understands the delicate nature of medical financing, especially when your credit history isn’t perfect. Traditional personal loans from major national banks often have rigid criteria that disqualify anyone with a single late payment or a high debt-to-income ratio.
This list highlights the top options available this year for those navigating the tricky waters of medical debt and reconstruction.
JetzLoan
Cherry
CareCredit
United Credit
Acorn Finance
MedLoan Finance
How These Medical Financing Options Were Evaluated
The selection process focused on accessibility for individuals with less-than-stellar credit histories. It is easy to find lenders for those with perfect scores, but the real challenge lies in finding institutions that don’t immediately slam the door shut. We looked for providers that offer high approval rates and transparent terms to prevent hidden surprises later.
A «hidden surprise» in medical financing often manifests as an unexpected origination fee or a sudden spike in APR after a promotional period ends. You don’t want to find out you are ineligible after you have already scheduled your surgery and perhaps even paid a non-refundable deposit.
Speed of funding and the ability to check rates without a hard credit pull were also vital. We prioritized services that offer instant or very fast decisions, ensuring that the path from consultation to the operating room is as smooth as possible. We specifically analyzed the «soft pull» mechanisms of each provider to ensure users could shop with confidence.
Lender Name
Loan Amount Range
Funding Speed
Credit Check Impact
JetzLoan
$500 – $35,000
As little as 24 hours
No hard credit pull
Cherry
See site
Immediate upon approval
No hard credit check
CareCredit
See site
Instant decisions
Prequalify with no impact
United Credit
See site
See site
See site
Acorn Finance
See site
See site
No credit score impact
MedLoan Finance
$500 – $100,000
See site
See site
Understanding the Cost of Credit: APR vs. Fixed Terms
Before selecting a lender, it is crucial to understand the mathematical difference between the types of financing available. Most medical loans fall into two categories: revolving credit and installment loans. Revolving credit, like CareCredit, functions much like a credit card. You have a limit, and as you pay it down, you can use that credit again.
This is excellent for ongoing treatments, like orthodontic work or multiple dermatological sessions, but it requires disciplined management to avoid high interest rates. If you let the balance sit, the costs can spiral quickly.
Installment loans, offered by providers like JetzLoan or MedLoan Finance, provide a lump sum upfront that you pay back in fixed monthly increments. This is often better for a one-time major surgery, such as a rhinoplasty or a tummy tuck, because it provides a predictable repayment schedule. When comparing offers, always look at the Annual Percentage Rate (APR), not just the monthly payment. A low monthly payment might seem attractive, but if it is spread over 60 months, you may end up paying double the original cost of the procedure in interest alone.
The Top-Rated Financing Solutions
1. JetzLoan
JetzLoan acts as a high-speed bridge for those needing quick cash for medical needs. It is designed for speed, aiming to get funds into your bank account in as little as 24 hours. This makes it a powerhouse for last-minute surgical requirements or unexpected medical costs that cannot wait, such as emergency dental work or urgent corrective procedures. (jetzloan.com)
The platform is incredibly user-friendly, allowing you to check rates in just two minutes. Because there is no hard credit pull, you can shop around without fear of lowering your score. This «soft pull» mechanism allows you to see your potential interest rate and term length before you commit to a formal application.
It is a practical choice for anyone who needs a significant amount, up to $35,000, without the usual bureaucratic delays associated with traditional bank loans. It gets the job done when timing is everything.
Pros: Extremely fast funding, no impact on credit score during checks, up to $35,000 available.
Cons: Maximum loan amount may be lower than some specialized medical loans.
2. Cherry
Cherry has become a massive name in the healthcare space, trusted by tens of thousands of providers. It is a favorite for patients who want a «no fuss» experience. The application process is lightning-fast, often taking only about 35 seconds to complete, which is ideal for busy people who are visiting multiple specialists in a single day.
This option is particularly strong for those seeking high approval rates. It offers a sense of ease that can alleviate the stress of medical debt. Many providers choose Cherry over other competitors because it simplifies the checkout process at the doctor’s office, making the transaction feel almost seamless.
It functions much like a digital payment service specifically tailored for the medical industry, removing the awkwardness of discussing finances in a clinical setting. You can focus on your health instead of your wallet.
Pros: Very high approval rates, instant approval, extremely fast application.
Cons: Approval is subject to provider participation and specific medical terms.
3. CareCredit
CareCredit is a household name in the wellness industry, accepted at hundreds of thousands of locations. It functions as a dedicated health and wellness credit card. This makes it highly versatile, as you can use it for a wide range of procedures beyond just cosmetic surgery, including vision care, veterinary services, and even some types of physical therapy.
The flexibility of this credit card is its greatest strength. It allows you to pay over time, which can help manage your cash flow while you recover. Many patients utilize the «deferred interest» promotional offers, which allow for 6, 12, or 24 months of interest-free payments.
However, this is a double-edged sword. If you fail to pay the full balance by the expiration date, interest is often backdated to the original purchase date. This can result in a massive, sudden bill that catches you completely off guard.
Cons: Requires credit approval; interest rates can be high if terms aren’t met.
4. United Credit
United Credit focuses on building long-term relationships rather than just closing a single transaction. They work with a variety of lenders to ensure that consumers have multiple options. This variety is a lifeline for those with varying credit profiles, from excellent to bad credit. Instead of a «one size fits all» approach, they act as a conduit to a wider market of lending specialists.
Their approach is centered around personal well-being and supporting the consumer’s journey. By maintaining a deep network of lenders, they can often find a path forward when a single bank might say no. This is particularly helpful for individuals who have been denied by major banks due to being «self-employed» or having a non-traditional income stream.
It is a solid choice for those who want a more personalized lending experience and a higher chance of approval. They look at the whole person, not just a number.
Pros: Wide variety of options through multiple lenders, supports diverse credit backgrounds.
Cons: The process may involve more steps due to the variety of lender options.
5. Acorn Finance
Acorn Finance operates somewhat differently by offering financing that is often used for larger home and medical projects. They specialize in connecting borrowers with personalized rates without the traditional sting of a credit score impact. It is a very transparent way to shop for rates, acting as an aggregator that brings various specialized lenders to one dashboard.
The platform is highly rated by users who appreciate the speed of the SMS and email application processes. Even if your credit is not perfect, they aim to find a contractor or provider who can accommodate your specific needs.
This makes them an excellent resource for complex medical transformations that involve multiple stages or providers, such as a full facial reconstruction or extensive orthopedic surgery involving several different specialists. It keeps everything in one place.
Pros: No credit score impact when checking rates, user-friendly SMS/Email applications.
Cons: More geared toward larger project financing rather than small cosmetic tweaks.
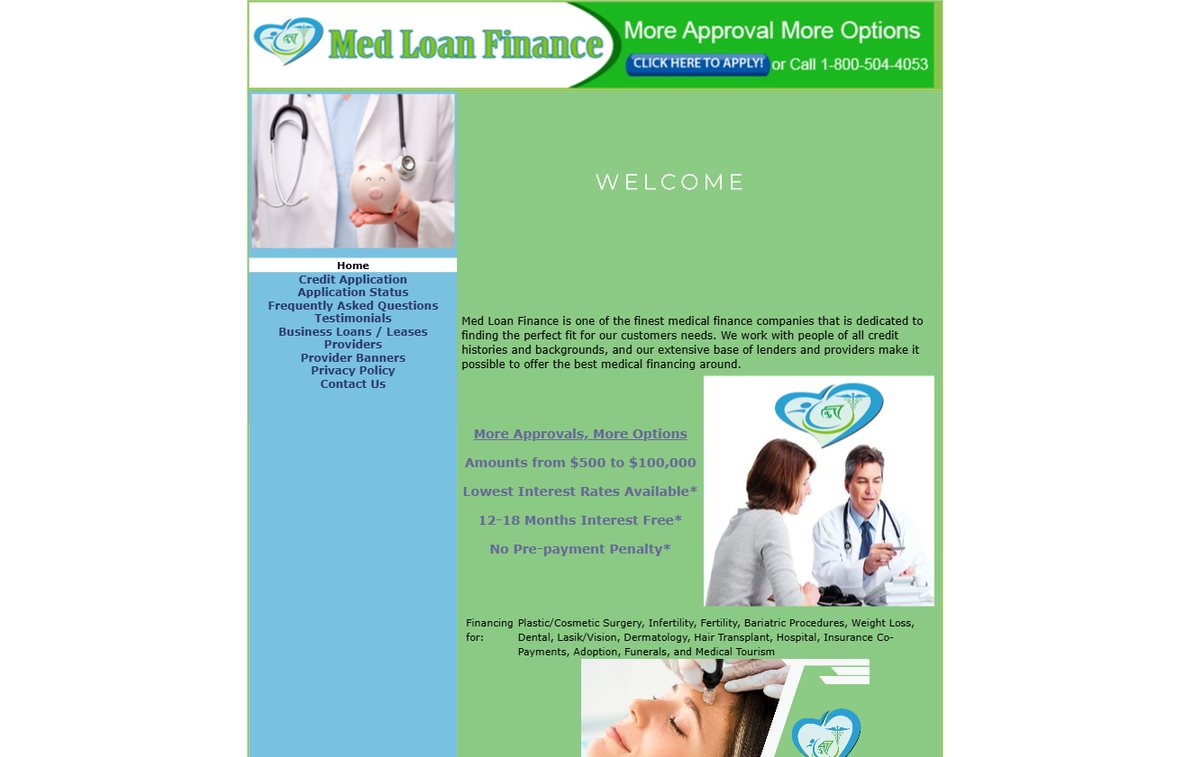
6. MedLoan Finance
MedLoan Finance is a dedicated player in the medical sector, focusing heavily on specific procedures like bariatric, dental, or cosmetic surgery. They are built to work with people of all credit histories and backgrounds, aiming to provide the «best medical financing around» through specialized medical underwriting.
With loan amounts reaching up to $100,000, this is a serious option for major reconstructive or aesthetic journeys. Unlike general-purpose personal loans, they understand the specific timelines of medical recovery. They offer specialized terms, including the potential for interest-free periods of 12 to 18 months.
This can be a massive relief during recovery when you may be unable to work for a short period due to the surgical procedure. It provides a cushion when you need it most.
Pros: High maximum loan amounts, specialized medical focus, potential for interest-free terms.
Cons: Terms and interest rates are subject to specific medical procedure types.
Navigating Your Financing Journey
Choosing a lender is not just about the lowest interest rate; it is about finding a partner that fits your specific surgical plan. If you need a quick fix for a small procedure, a fast-funding option like JetzLoan might be your best bet. However, if you are planning a major reconstructive surgery, the higher limits of MedLoan Finance might be necessary to cover the surgeon, the anesthesia, the facility fees, and the post-operative care.
Avoid the mistake of applying for multiple hard credit pulls in a short window. This can make you look desperate to lenders and drop your score further. Each time a lender performs a «hard pull» to make a final decision, it leaves a footprint on your credit report.
Instead, always use the «no impact» or «pre-qualification» tools first. This allows you to compare your real options without any financial penalty, letting you build a mental roadmap of your potential debt before you commit. It is better to know the cost of the money before you spend the money.
Lastly, read the fine print regarding «interest-free» periods. Many medical lenders offer promotional windows, but if you miss a payment or fail to pay the balance by a certain date, you could be hit with retroactive interest. This is not just a small fee; it can be thousands of dollars depending on the principal amount. Stay organized, set up autopay to avoid accidental missed payments, and treat your medical loan with the same seriousness as a mortgage.
Top 6 Lenders for Bad Credit Loans in Arkansas: A 2026 Review
Last updated: 2026-10-16
Trying to manage money in the Natural State can feel like hacking through a thicket when your credit score isn’t exactly where you want it. Many Arkansans deal with sudden car repairs or medical bills without any safety net. When the bills start piling up on the kitchen table, finding a reliable lender becomes the top priority.
Living in Little Rock during a humid summer means a broken HVAC system isn’t just an inconvenience; it’s a crisis. Similarly, if a truck used for work in Northwest Arkansas needs an urgent repair, the need for quick cash hits hard. The pressure to find liquidity fast can be overwhelming when you’re just trying to keep things running.
When you search for relief, look for transparency and speed. You need to know the total cost of borrowing before any ink hits the paper. This list helps clarify which providers offer the best paths for those working to rebuild their financial footing. A single hidden fee or a misunderstood rate can turn a necessary cash infusion into a long-term burden.
FastLendGo
Balance Credit
NetCredit
Rent-A-Center
Roadrunner Financial
Best Egg
How We Evaluated Arkansas Lending Options
We measured each provider against specific criteria relevant to the Arkansas market. Our focus was on how easy it is to apply without hurting a credit score and how quickly funds actually hit a bank account. Speed is often the difference between a minor hiccup and a major crisis. If a utility shut-off notice arrives, a lender taking five days to process is far less useful than one offering same-day funding.
We also looked at loan amounts and repayment flexibility. A lender that only offers tiny sums might not help with a $3,000 transmission replacement. We prioritized companies that consider people with less-than-perfect credit history. This ensures the list covers a variety of needs, from a quick $500 bridge to $50,000 for debt consolidation.
The goal was to find options that actually work for real people. We didn’t want a list of companies that look good on paper but fail when you actually need the cash. Every provider here was vetted for their ability to deliver on their promises in the real world.
Lender Name
Max Loan Amount
Funding Speed
Credit Requirements
FastLendGo
See site
See site
Bad/Fair/Good
Balance Credit
$4,000
Next business day
Inclusive consideration
NetCredit
$10,000
Same-day available
See site
Rent-A-Center
See site
See site
No credit needed
Roadrunner Financial
See site
Real-time decision
All credit welcome
Best Egg
$50,000
See site
See site
The Best Lenders for Arkansas Residents
1. FastLendGo
FastLendGo helps people who need quick cash for specific life events. Whether it is a sudden dental bill or an auto repair, this provider focuses on speed. It is a practical choice for people who want to compare local options without a long, drawn-out process. They understand that emergencies don’t wait for bank holidays. (fastlendgo.com)
This lender is useful for those who might not qualify for traditional bank loans due to a thin credit file. They offer various tiers, from small $500 loans for immediate necessities up to larger personal financing for significant life changes. It is a versatile tool for navigating emergencies, sitting between high-interest payday loans and restrictive traditional banks.
The application process is built for speed. If you are facing a sudden expense, you can’t afford to wait weeks for an answer. They aim to get you an answer when you actually need it.
Pros:
Quick access to various loan amounts
Covers specific needs like dental or roof financing
Simple online comparison process
Cons:
Website structure can be complex to navigate
2. Balance Credit
Balance Credit acts as a partner for those in tight financial spots. Sometimes you just need cash to keep things moving, like paying a deposit on a new apartment or covering a utility spike. Their focus is on simplicity. They try to ensure the application doesn’t add stress through endless paperwork or confusing jargon.
One standout feature is the lack of penalties for paying off a loan early. This is a huge win for anyone trying to save money on interest. If you get a tax refund or a work bonus, you can apply that money immediately toward your principal. You won’t be punished for being proactive with your finances.
By removing prepayment penalties, they give you more control over your debt. You won’t find yourself trapped in a loan just because you tried to be responsible with your extra cash.
Pros:
No penalties for early payoffs
Fast funding by the next business day
No impact to credit score during eligibility check
Cons:
Loan amounts are capped at a relatively low $4,000
3. NetCredit
NetCredit operates on the idea that you are more than just a number in a database. They use algorithms to look at a broader picture of your financial health. This can be a lifesaver for people who have a few hiccups in their credit history, like a single late payment from a year ago, but are otherwise stable earners.
With loans reaching up to $10,000, they offer more substantial support than many quick-cash providers. This amount is often the sweet spot for consolidating several smaller, high-interest credit card balances into one single monthly payment. It’s a way to simplify your life without a massive amount of paperwork.
You can check your eligibility without affecting your FICO score. This makes it a low-risk way to explore your options before you commit to a formal application. It’s a smart way to see what you qualify for without any guesswork.
Pros:
Higher loan limits up to $10,000
Same-day funding availability
Holistic review of applicants
Cons:
Terms may vary based on underwriting
4. Rent-A-Center
Rent-A-Center takes a different approach by focusing on rent-to-own solutions. Instead of a traditional cash loan, you are getting the items you need through a lease-to-own model. This is ideal for furniture, electronics, or appliances when an upfront cost is out of reach and you need to furnish a home immediately.
This is a «no credit needed» path. It is a game-changer for those who have been shut out of the traditional banking system or those who simply do not want a hard credit inquiry. It allows for immediate access to essentials like a refrigerator or a sofa with very low startup costs.
This model works well for short-term cash flow gaps. If you need a washing machine today to keep your life running, this is a practical way to get it without needing a bank’s approval.
Pros:
No credit check required for many items
Low entry cost to get started
Wide variety of household goods
Cons:
Total cost over time can be high due to rent structure
5. Roadrunner Financial
Roadrunner Financial is a specialized player for powersports enthusiasts. If you want a new ATV, motorcycle, or even a golf cart, this is a dedicated path. They focus on getting you riding quickly without the usual dealership haggling or the long wait times of big-box financing departments.
They offer a quick pre-qualification process that gives you a real-time decision. This is perfect for someone who has found a great deal at a local dealership in Fayetteville or Fort Smith and needs to act fast. Knowing your budget and availability upfront lets you walk into a dealership with confidence.
They understand the specific needs of this market, such as seasonal riding needs. It’s a niche service that skips the generalities and goes straight to what you actually need to buy.
Pros:
Specialized for powersports vehicles
Real-time decisions with no credit impact
Competitive rates valid for 30 days
Cons:
Highly niche; not for general personal use
6. Best Egg
Best Egg is a heavy hitter in the personal loan space, offering much larger sums for debt consolidation. If you are trying to roll several high-interest payments into one manageable monthly chunk, this is a strong candidate. They use technology to simplify the user experience rather than making it complicated.
They offer fixed interest rates and flexible terms, which provides more stability than variable-rate loans. For those with a bit more collateral, like home fixtures or other assets, they can even offer lower rates to help you save money over the life of the loan.
This makes them a premium choice for those looking to move away from survival mode and into long-term financial planning. It’s about making a big move to get your finances back on track permanently.
Pros:
Large loan amounts up to $50,000
Fixed interest rates provide predictability
Excellent customer reviews and BBB rating
Cons:
May require better credit for the best rates
How to Compare Loan Terms Like a Pro
Before you sign a loan agreement, understand the difference between the «APR» and the «Interest Rate.» The interest rate only tells you the cost of the principal, while the APR includes other costs like origination or processing fees. When comparing two lenders, always look at the APR to see the true cost of the money.
Consider these three comparison steps:
Calculate the Total Repayment: Take your monthly payment and multiply it by the number of months in the term. Subtract the original loan amount from this total to see exactly how much you are paying in interest and fees.
Check for Prepayment Penalties: As mentioned with Balance Credit, some lenders charge you a fee for paying the loan back early. Always prioritize lenders that allow early payoff without extra charges.
Evaluate the Monthly Impact: Look at your current monthly budget. Does the new loan payment fit comfortably, or does it leave you with zero margin for error if another emergency arises?
Common Pitfalls to Avoid in Arkansas
Navigating your borrowing journey requires vigilance. Choosing a lender isn’t just about the lowest number on the screen. You must look at the fine print to ensure you aren’t walking into a trap. Always check for hidden fees, like origination costs or late penalties, which can quietly balloon your debt.
For example, a $1,000 loan with a $100 origination fee means you only actually receive $900, but you are paying interest on the full $1,000. Avoid the mistake of taking out a loan you cannot afford to pay back. It sounds simple, but when you are in a crisis, it is easy to lose sight of the monthly obligation.
A loan is a tool to solve a problem, not a way to create a larger one later. If you are borrowing money to pay off other debt, ensure the new interest rate is significantly lower than the debt you are replacing. Otherwise, you are simply shuffling debt around without actually solving the problem.
Finally, always compare the total cost of credit. A lender might offer a low monthly payment, but if the term is three years long, you might end up paying double what you borrowed. Take a deep breath, read the terms, and pick the option that truly fits your life.
Top 5 Lenders for Personal Loans for Low Income Individuals in 2026
Last updated: 2026-10-16
Trying to find breathing room when your paycheck barely covers the basics feels like swimming against a heavy tide. You might find yourself staring at a mountain of bills, wondering if there is a lifeline available that doesn’t require a perfect credit score. It is a stressful place to be.
Unexpected expenses have a way of derailing a carefully managed budget in a single afternoon. A sudden transmission failure in your car, an unexpected medical co-pay, or a seasonal spike in utility costs can throw everything off balance. When things get tight, you need options that work for your specific situation.
When searching for a way forward, look past the flashy marketing. You need to know how fast the money actually arrives, what the total cost looks like over time, and whether checking your rate will tank your score. The difference between a helpful tool and a financial burden often lies in the fine print of the Annual Percentage Rate (APR) and the repayment terms.
This list focuses on lenders that offer accessible paths for those often overlooked by traditional big banks. We have included a spectrum of options, ranging from high-speed emergency funds to long-term debt consolidation tools.
JetzLoan
Best Egg
Avant
OneMain Financial
OppLoans
How These Lenders Were Evaluated
Our selection process involved looking at how these companies treat borrowers who might be struggling. We focused heavily on accessibility, specifically looking for lenders that offer quick decisions. We wanted to find companies that don’t require a hard credit pull just to see your options. It is vital to know if a lender will actually talk to you or if they will just send a rejection letter.
We examined their reputation for customer service and the clarity of their fee structures. We also looked at how they handle various credit profiles to ensure they are useful for a wide range of people. Transparency is not a luxury; it is a necessity when you are trying to manage your money.
Speed and transparency were also key pillars of this evaluation. For someone living paycheck to paycheck, waiting ten business days for funds is not an option. We prioritized companies that provide rapid funding, whether that is within twenty-four hours or even the same business day. We want the help to arrive when it is actually needed most.
We also looked at the «soft inquiry» model. This allows you to shop for the best rate without the penalty of a hard credit pull. This feature is critical for anyone trying to protect their remaining credit health while looking for better terms.
Lender Name
Loan Amount Range
Funding Speed
Credit Impact Check
JetzLoan
$500 – $35,000
As little as 24 hours
No hard credit pull
Best Egg
Up to $50,000
See site
See site
Avant
See site
See site
OneMain Financial
$1,500 – $30,000
As soon as 1 hour
No credit score impact
OppLoans
See site
Same-day funding available
Does not affect FICO score
Top Rated Lenders for Accessible Credit
1. JetzLoan
JetzLoan connects borrowers with a variety of top personal loan lenders in just a few minutes. It is designed for speed and simplicity. This makes it a strong choice for anyone needing to consolidate debt or cover a vehicle loan quickly. The process is streamlined to keep the stress to a minimum. It uses a digital-first approach for those who cannot afford to wait for traditional banking cycles. (jetzloan.com)
This service is particularly helpful for those who are nervous about their credit score. Because they offer a way to check rates without a hard credit pull, you can shop around without fear of damaging your standing. This «pre-qualification» phase is essential. It allows you to see a potential interest rate and term length before you commit to a formal application.
They have built a reputation for reliability in a crowded market. With a 4.7-star rating and over 500,000 loans funded, they know how to deliver. It is a solid option if you need to see your numbers before you make a big decision.
Pros:
No hard credit pull to check rates
Fast funding in as little as 24 hours
Up to $35,000 in loan amounts
Cons:
Limited to a maximum of $35,000
2. Best Egg
Best Egg is a major player in the personal loan space. They are well-known for helping people consolidate high-interest debt. Their goal is to simplify your monthly payments. They aim to turn a chaotic pile of bills, such as multiple credit card balances or high-interest medical debt, into one manageable chunk. By consolidating, you can often secure a lower interest rate than what you are currently paying on individual cards.
This can lead to significant long-term savings and a clearer path to being debt-free. They have built significant trust through an A+ rating from the Better Business Bureau and thousands of positive reviews. For homeowners, there might be additional opportunities to access lower rates by using fixtures like cabinets or vanities as collateral. However, most users opt for their standard unsecured personal loans.
It is a more structured approach to borrowing. This makes it ideal for those looking for a long-term financial strategy rather than a quick fix. If you want to get organized and stay organized, this might be the right fit.
Pros:
High loan limits up to $50,000
Excellent BBB rating
Potential homeowner discounts
Cons:
Requires more information for the application
3. Avant
Avant focuses on the idea that everyone’s financial journey is unique. They offer a variety of tools and solutions, including credit cards and installment loans. Their services are specifically designed to help people move forward. Whether you are covering an unexpected emergency or funding a home improvement project, they aim to provide options that fit your life.
Unlike banks that use rigid, automated scoring, Avant looks at a broader picture of your financial health. They position themselves as a partner in your financial life. This offers flexible choices for those who might find traditional banking difficult. It is a versatile option for those who need something specific, like a debt consolidation loan, rather than a one-size-fits-all solution.
Their platform is built for those seeking a clear answer to difficult financial questions. They provide a streamlined digital experience that minimizes the paperwork typically associated with personal loans. It is built for the modern borrower who wants answers, not endless forms.
Pros:
Flexible loan and credit card options
Designed for various life stages
Focus on moving forward financially
Cons:
Specific qualifying criteria not always transparent
4. OneMain Financial
OneMain Financial is a standout for those who prefer a human touch. With over 1,300 branches, they offer the ability to speak with a real person. This can be a lifeline when you are confused by complex terms or when your situation has nuances that an algorithm might miss. This physical presence provides a level of security and accessibility for those who prefer to handle their business in person.
The speed of their service is quite impressive. Money could potentially be available just one hour after signing. They offer loans ranging from $1,500 to $30,000 with fixed monthly payments. This helps with budgeting because you know exactly what will leave your bank account each month. This predictability is vital for families living on a strict monthly budget.
It is an excellent choice for someone who needs cash almost immediately to handle a pressing matter. If you have an urgent car repair or a sudden home maintenance issue, having a local branch to visit can provide peace of mind. You can walk in, talk it out, and get moving.
Pros:
Extensive branch network for in-person help
Very fast funding after signing
Fixed monthly payments for 24-60 months
Cons:
Interest rates can vary significantly
5. OppLoans
OppLoans is built around the idea that a credit score doesn’t tell the whole story. Their bank partners look at more than just that single number. They consider factors like your employment history and income stability. This makes them a viable option for those who have been turned down elsewhere due to a recent dip in credit caused by a life event.
If you have faced a medical emergency or a period of unemployment, they might still work with you. It is a practical solution for people who need to avoid hidden fees and complicated fine print. The application process is remarkably quick, with decisions often arriving in minutes. If you are approved, you might see the money in your account as early as the same business day.
This makes them a high-speed option for emergency situations where every hour counts. Whether you are trying to prevent a utility shut-off or covering an immediate cost of living gap, they provide quick relief. Their transparency regarding fees ensures you aren’t surprised by the total cost of borrowing.
Pros:
Same-day funding is a possibility
Does not affect FICO credit score to apply
No hidden fees
Cons:
May not be suitable for long-term debt
The Total Cost of Borrowing
When you are in a rush, the interest rate is often the first thing people overlook. However, it is the most important number on the page. You must distinguish between the APR (Annual Percentage Rate) and the simple interest rate. The APR is a more accurate representation of the cost because it includes interest and any mandatory fees, such as origination or processing costs.
For example, a loan might have a 10% interest rate, but if there is a $300 origination fee on a $2,000 loan, your APR will be significantly higher. To calculate the true impact on your budget, perform a quick «monthly impact test» before signing. Take the total monthly payment and multiply it by the number of months in your term. Subtract the original amount you borrowed from that total.
The result is the actual cost of the loan in dollars. If you are borrowing $2,000 to cover a repair, but you will end up paying $600 in interest over the life of the loan, ask yourself if that is a sustainable cost for your current budget. Understanding this math prevents the «debt trap» where you are working just to pay off the interest on previous loans.
Common Pitfalls to Avoid When Applying
One common mistake is borrowing more than you can realistically pay back each month. It might be tempting to take the maximum amount offered. For instance, you might take a $5,000 loan when you only need $3,500. However, a higher principal amount means a higher monthly payment. This can lead to a cycle of debt that is hard to escape, especially if your income fluctuates.
Always build a small buffer into your budget before committing to a new monthly obligation. This helps account for unexpected fluctuations in your regular living expenses. You don’t want your new loan payment to be the reason you can’t pay your electric bill next month.
Another trap is ignoring the impact of different types of inquiries. While many of these lenders allow you to check your rate without hurting your score through a «soft pull,» a «hard inquiry» will occur once you actually accept the loan. This is a formal request from the lender to view your full credit report, and it can cause a temporary dip in your score. Be sure you are certain about the terms before you move from the «checking» phase to the «signing» phase.
Additionally, avoid the temptation of «rolling over» short-term loans into new loans. This is a common way that small debts grow into unmanageable financial burdens. It feels like you are staying afloat, but you are actually just sinking more slowly.
Walking into a showroom and falling in love with a velvet sofa is a feeling most of us know well. However, that immediate spark often hits a brick wall when the price tag comes into view. Financing lets you bring that comfort home today by spreading the cost over several months or even years.
Deferring large expenses helps manage modern household needs. It is especially helpful when moving into a new place or replacing a mattress or dining table. You shouldn’t have to wait for a savings account to catch up just to sleep on a decent bed.
Picking a lender involves more than just looking at a monthly payment. You have to dig into the fine print and interest rates. You also need to know if a provider requires a perfect credit score. A high interest rate can effectively double the cost of your furniture. A $1,000 sofa can quickly become a $2,000 expense by the time you make that final installment.
Look past the initial aesthetic appeal. You must evaluate the mathematical reality of your debt. This review looks at the top contenders for home furnishings debt. Whether you want a short-term promotion or a long-term plan, knowing your options is the first step toward responsible decorating.
Furniture Row
FastLendGo
Jordan's
Rent-A-Center
CashUSA
How These Lenders Were Evaluated
Evaluating furniture financing requires looking beyond the furniture itself. We focused on how flexible the terms are and how easy the application process feels. A zero percent interest offer sounds like a dream. However, those plans usually come with strict credit requirements.
Many «no interest if paid in full» plans demand a high FICO score. Lenders want to see stable, verifiable income to ensure they aren’t taking on too much risk. We also looked at how quickly you can actually get the funds. Some lenders focus on those with established credit histories to offer the lowest APRs. Others cater to people needing a second chance after credit hiccups.
We weighed the speed of approval against the total cost of borrowing. This provides a clear picture for every budget. Our evaluation analyzed these specific metrics:
Speed of Approval: How long from clicking «apply» to having credit ready at the register?
Transparency: Does the lender clearly state all fees, or are there hidden origination fees or late penalties?
Flexibility: Can you pay the loan off early without penalties? This is vital if you plan to make extra payments to save on interest.
Minimum Requirements: Is there a hard minimum credit score or a pathway for those with limited history?
Lender
Max Loan Amount
Interest Rate Options
Credit Requirements
Furniture Row
see site
0% APR available
Subject to approval
FastLendGo
$5,000
see site
Bad, Fair, and Good
Jordan’s
see site
0% APR for 24 months
Subject to approval
Rent-A-Center
see site
Rent-to-own
No credit needed
CashUSA
$10,000
see site
see site
Top Furniture Financing Rankings
1. Furniture Row
Furniture Row is a strong choice for those combining high-quality goods with specialized financial tools. They partner with various institutions to offer promotional terms. This variety helps shoppers find a plan that fits their specific lifestyle and budget. They offer a spectrum of options rather than a one-size-fits-all approach.
The availability of 0% interest financing is a major draw. For those who qualify, this avoids the heavy weight of interest. Imagine buying a $3,000 sectional sofa. With 0% interest over 12 months, you pay $250 per month. If you were forced into a standard 18% APR loan, that same sofa could cost you nearly $3,500.
This makes premium items feel much more attainable for the average household. Just make sure you can manage the monthly cash flow. It is a great way to get high-end items without a massive upfront hit to your bank account.
Pros:
Special 0% interest financing available.
Large selection of living, dining, and bedroom furniture.
Options for both in-store and online shopping.
Cons:
Requires qualifying for specific promotional terms.
Missing a single payment can often result in «retroactive interest,» where you are charged interest from the original purchase date.
2. FastLendGo
FastLendGo works well for anyone needing quick access to cash for various needs. While they handle more than just furniture, their personal loan structures are ideal for furnishing an entire apartment. Unlike store-specific credit, a personal loan from FastLendGo gives you total freedom. You can shop at multiple stores to maximize value.
They are particularly useful if your credit score isn’t exactly where you want it to be. By offering solutions for bad, fair, and good credit, they open doors that many traditional banks slam shut. This is a streamlined way to compare options without the headache of visiting multiple branches. It is a digital-first approach for a fast-moving world.
This is helpful if you need to furnish a rental property on a tight deadline. You get the cash in a lump sum and can shop wherever you please. It removes the restriction of being tied to a single retailer’s inventory.
Pros:
Covers a wide range of credit scores.
Provides loans from $500 up to $5,000.
Fast online application process.
Cons:
Primarily focused on personal loans rather than direct store credit.
Terms may be shorter than long-term furniture-specific installments.
3. Jordan’s
Jordan’s Furniture is a major player known for an impressive showroom experience. They offer sophisticated financing that makes high-end purchases feel manageable. Their promotions often include perks like free white glove delivery. This adds massive value to a large purchase by saving you labor and stress.
White glove delivery includes bringing items inside, assembling them, and removing all the packaging. When paired with high-quality goods, the financing becomes even more attractive. The 24-month 0% APR option is a standout feature for many buyers. It allows you to upgrade your bedroom or living room without the immediate sting of a massive bill.
It is a strategic choice for those with a steady income who prefer to preserve cash for rent or emergency savings. This «interest-free» window acts as a short-term loan. It lets your money work elsewhere while you enjoy your new home comforts.
Pros:
Promotional 0% APR for 24 months.
White glove delivery options available.
Wide variety of home categories including gaming and outdoor.
Cons:
Promotional rates are subject to credit approval.
High-end inventory can lead to high total debt if not carefully managed.
4. Rent-A-Center
Rent-A-Center is the go-to option for those who want to avoid the traditional credit system entirely. Their rent-to-own model is built on flexibility. You can get the gear you need today without the immediate pressure of a long-term commitment or a formal credit check. This is essentially a lease-to-own agreement.
You pay for the use of the item, with the option to own it after a set number of payments. This is a lifeline for individuals in transitional phases of life. Students or people moving for seasonal work often find this model helpful. You can start with a small down payment and upgrade as your needs evolve.
For instance, you might start with a basic coffee table. After a few months of successful payments, you could swap it for a larger entertainment center. It provides a level of freedom that standard installment loans simply do not offer. You aren’t locked into one piece of furniture forever.
Pros:
No credit needed to get started.
High flexibility to upgrade or change plans.
Low entry cost to start renting.
Cons:
Rent-to-own models can be more expensive in the long run.
If you do not complete the full term, you do not own the items and have essentially paid for «renting» without equity.
5. CashUSA
CashUSA operates as a digital connector. They help users find personal loans that meet specific criteria. If you need up to $10,000 to remodel a room, this service can point you toward a lender. It is a modern, efficient way to shop for credit. It works much like a comparison engine for your finances.
The process is designed to be simple. It typically involves just four steps: application, comparison, selection, and funding. While they may connect you to debt relief if a loan isn’t found, their primary goal is facilitating connections. This is ideal for the tech-savvy consumer who wants to see multiple options on a single screen.
You can skip the hours spent on the phone with different banks. Instead, you get a streamlined online experience. It saves time when you are looking to make significant household changes quickly.
Pros:
Potential for loans up to $10,000.
Fast connection to lenders.
Simple, streamlined online application.
Cons:
May provide marketing offers instead of loans if not matched.
Essential Questions to Ask Before Signing
Before you settle on a financing plan, perform a «stress test» on your budget. Many consumers fall into the trap of looking only at the monthly payment. A $50 monthly payment sounds incredibly manageable. However, if that payment lasts for 60 months, you are paying for that item for five years.
If the interest rate is high, you might end up paying for the item twice. Use this checklist when talking to a salesperson or a loan officer. It will help you avoid expensive surprises later on:
«What is the total cost of the item including all interest and fees?» This is the most important number in the transaction.
«Is there a penalty for early repayment?» If you get a bonus and want to pay off your sofa in month six, you should be allowed to do so without a penalty.
«What happens if I am one day late on a payment?» Some contracts have strict «default» clauses where you lose all your 0% interest benefits and are charged backdated interest immediately.
«Are there any origination fees or service charges?» Some lenders add a $100 «processing fee» upfront that isn’t included in the advertised monthly payment.
How to Choose the Right Plan
Before signing your name, look closely at the total cost of ownership. A low monthly payment can be deceptive if it is stretched over a decade. Always ask, «What is the total amount I will have paid by the end of this term?» This simple math reveals the true cost of the «deal.»
Avoid the trap of taking on more debt than your monthly budget allows. It is easy to get swept up in the excitement of a new dining set. However, financial stability is the foundation of a happy home. If you choose a rent-to-own option, remember you are paying for flexibility, not necessarily the lowest price.
Rent-to-own is a service for convenience. Personal loans and store credit are tools for ownership and building equity. Always check the interest requirements. If you qualify for a 0% APR deal, ensure you understand the penalties for a single late payment. One missed deadline can trigger a massive interest spike.
Stay organized and stay diligent. Use a calendar to track your payment dates. Consider setting up autopay so you never miss a beat. By being proactive, you can enjoy your beautiful new furniture without the lingering stress of debt.
Finding the right dirt is often easier than finding the money to buy it. For many dreamers, the idea of owning a slice of the countryside or a quiet wooded lot feels just out of reach. Credit histories often act as a wall. Traditional banks frequently turn up their noses when a score dips below certain numbers, often demanding a 20% to 30% down payment that most first-time buyers simply do not have sitting in a savings account.
They view raw land as a high-risk asset. Unlike a residential home, land doesn’t offer a physical structure to serve as collateral if the loan goes sour. This makes securing financing a bit of a climb. You have to find lenders who see the value in the soil rather than just the digits on a credit report.
This list focuses on finding paths through those financial hurdles. Whether you want a small garden plot, a few acres for a weekend retreat, or a massive acreage for a homestead, you need to know your options. Understanding the difference between a «raw land loan» (land with nothing on it) and a «finished lot» (land with utility access and road frontage) is your first step toward matching with the right capital provider.
Acorn Finance
JetzLoan
LightStream
Country Bank
Lendersa
USDA
How These Land Loan Options Were Evaluated
The evaluation process focused on accessibility for different credit profiles. Not every lender is built for the same purpose. It is vital to know the distinction between personal loans, hard money, and government-backed programs. A lender that provides a quick cash injection might not be the right fit for a long-term mortgage. For example, a personal loan might offer speed, but you will likely face a higher interest rate than a traditional mortgage secured by the property itself.
Conversely, a traditional mortgage might take 45 days to close. In that time, your dream property might be sold to someone else. Speed of funding and the impact of credit inquiries were also key metrics. Some providers allow you to check rates without hurting your score. This is a lifesaver when you are trying to understand your borrowing power before committing to an offer.
We prioritized transparency. We looked at how quickly funds move, the complexity of the application, and what kind of collateral is actually required for the deal. We looked specifically at whether the lender requires a «hard pull» that stays on your report or a «soft pull» which is just an inquiry for informational purposes. It makes a world of difference when you are on a tight budget.
Lender Name
Max Loan Amount
Funding Speed
Credit Requirement
Best For
Acorn Finance
See site
See site
Good & Bad Credit
Contractor/Home Improvement
JetzLoan
$50,000
24 Hours
No Hard Pull Check
Fast Cash/Debt Consolidation
LightStream
$100,000
See site
Good to Excellent
High Credit Borrowers
Country Bank
See site
60 Day Rate Lock
Subject to Approval
Raw Land/Buildable Lots
Lendersa
See site
Fast Closing
Varies (Hard Money)
Fix and Flip/Investors
USDA
See site
See site
Varies
Rural Development/Homes
Ranking of Land Loan Providers
1. Acorn Finance
Acorn Finance acts as a bridge between borrowers and various financing options. They specialize in providing $0 dealer fees. This is a breath of fresh air in an industry known for hidden costs and service charges that can add thousands to your total loan amount. It is a solid choice if you need to combine land acquisition with immediate improvements, such as clearing trees or installing a driveway.
This provider is particularly useful for those who need to get a project moving quickly. Because they cater to both good and bad credit, the barrier to entry is significantly lower than a standard big-box bank. Instead of being judged solely on a FICO score, the variety of lenders they connect you with means there is a higher probability of finding a specialist who understands your specific situation.
It is a practical tool for the modern borrower who needs flexibility. You won’t find yourself stuck in a loop of denials if you have a complicated financial history. They focus on matching you with someone who can actually say «yes» to your project.
Pros:
$0 dealer fees for contractors and borrowers
Personalized rates with no credit score impact during checking
High customer satisfaction with 4.3 stars on Trustpilot
Cons:
May not offer the lowest rates compared to prime lenders
2. JetzLoan
When time is of the essence, JetzLoan moves with impressive speed. They can deposit funds in as little as 24 hours. This makes them a go-to for urgent land deals or consolidation. This speed is essential in competitive markets where a seller might be looking for a «cash offer» to bypass the lengthy appraisal and inspection processes required by traditional banks.
The application process is remarkably streamlined. It takes only about two minutes to complete. This makes it an ideal option for someone who has found a parcel of land at an auction and needs to secure funds immediately to show proof of capability. The ability to check rates without a hard credit pull is a major advantage for those with sensitive credit. This allows a borrower to shop around without fear of further damaging their score.
It is a high-speed option for a fast-paced market. If you find that perfect lot on a Friday afternoon, you don’t want to be waiting until next month to prove you can pay for it. JetzLoan fills that gap for those who need to act fast.
Pros:
Funding in as little as 24 hours
No hard credit pull to check rates
High loan limits up to $50,000
Cons:
Limited to personal loan structures rather than traditional land mortgages
3. LightStream
LightStream is a different beast entirely. They cater to those who have already climbed the credit ladder. They offer low fixed rates that are hard to beat if you have good to excellent credit. It is a premium service for those who want stability and predictability. You can lock in a rate and know exactly what your monthly payment will be for the duration of the loan.
The loan amounts can reach up to $100,000. This provides significant breathing room for substantial land purchases or for purchasing a large plot to subdivide. However, if your credit is currently in the «bad» category, this particular door will likely remain closed. They use automated underwriting processes that prioritize high FICO scores and stable income history.
It is a destination for the credit-worthy who want to avoid the higher interest rates of subprime lenders. If your finances are in order, this is often the most efficient way to move forward. They make the process incredibly smooth for those who meet their criteria.
Pros:
Low fixed interest rates
Loan amounts up to $100,000
Highly reputable through Truist
Cons:
Requires good to excellent credit; not for bad credit
4. Country Bank
Country Bank offers a more traditional, community-focused approach to lending. They are an FDIC-insured institution that understands the nuance of land in ways a large national bank cannot. While a national bank might reject a loan for a lot that has no paved road access, a community-focused bank understands the local zoning laws and the intrinsic value of that specific piece of geography.
One standout feature is their 60-day rate lock, which provides a sense of security in a volatile market. This allows a buyer to plan their next steps, such as hiring an architect or a surveyor, without worrying that interest rates will spike before they can close the deal. They provide tailored solutions for both raw land and buildable lots. They recognize that the risk profile of each is vastly different.
This is a great choice for someone looking for a long-term relationship with their lender. They know the area and they know the land. That local knowledge can be the difference between a deal falling through and a deal closing smoothly.
Pros:
60-day rate lock availability
FDIC-insured security
Offers financing for both raw and buildable land
Cons:
Standard bank approval processes can be rigorous
5. Lendersa
Lendersa is built for the investor who needs to move at the speed of light. Using AI to match borrowers with hundreds of hard money lenders and private investors, they optimize for closing speed. This is a high-octane option for real estate professionals who specialize in land flipping or quick acquisitions for development projects. While a traditional bank might take weeks to verify surveys, Lendersa’s network is built for rapid movement.
If you are looking to jump into an auction or a fast-moving «fix and flip» scenario, this is where you look. They focus on getting the deal closed in days rather than months. This is crucial when competition is fierce and a seller demands a quick close. They cover both residential and commercial property types, providing a wide net for diverse investment strategies.
It is not for everyone, as the terms are often quite different from a standard mortgage. However, for the professional investor, the speed can be worth the premium. It is all about how fast you can turn the property around for your next move.
Pros:
Uses AI to match lenders and optimize rates
Designed for fast closing and auctions
Covers residential and commercial property types
Cons:
Hard money terms can be much more expensive than traditional loans
6. USDA
The USDA is a government-backed option that focuses on the backbone of the country: rural development. They provide loans and grants aimed at helping people buy, build, or repair homes in specific rural areas. This is a mission-driven approach to lending designed to prevent rural depopulation by making it easier for young families and homesteaders to establish roots.
This is an excellent path for those looking to live in a rural setting and build a life from the ground up. The programs are designed to strengthen rural economies and expand opportunities for families who might otherwise be overlooked due to low down payments or specific income requirements. If you qualify, this can be one of the most affordable ways to acquire property in the country.
It requires a bit more paperwork and a specific location, but the payoff is significant. It is a program built for people, not just for profit. If you fit the criteria, it is a very powerful tool for homeownership.
Pros:
Government-backed stability and support
Focuses on rural economic development
Offers various programs including grants and loans
Cons:
Strict geographic requirements for eligibility
Understanding Land vs. Home Loans
Before applying, it is vital to understand the fundamental differences in how lenders view land versus a residential house. When you buy a house, the building itself acts as security. If you stop paying, the bank can sell the house and recoup their money. When you buy land, the security is just the dirt. If the market for that specific area dips, the land may not be worth what you paid for it, making it much riskier for the lender.
Because of this risk, land loans often require more from the borrower. You might face higher down payments, often 20% to 50% for raw land. You may also see higher interest rates than traditional residential mortgages. Lenders often demand more extensive documentation regarding access, easements, and utilities. In some cases, especially with hard money, you might even see short-term repayment options.
Essential Steps for Securing Your Land Deal
To ensure you aren’t left with a beautiful piece of property that is impossible to live on, follow these specific steps during your due diligence phase:
Verify Access: Never assume a dirt path is a legal right-of-way. Ensure the property has «legal access» to a public road. Without this, the land is virtually unmarketable and unfinanceable.
Check Utilities: Ask for a «perc test» if you plan to install a septic system. If the soil doesn’t drain properly, you might be unable to build a home. Additionally, check the cost to bring electricity to the site; running power lines can cost tens of thousands of dollars.
Review Zoning: Just because it is «rural» doesn’t mean you can build whatever you want. Check local ordinances for setbacks, minimum acreage requirements, and restrictions on livestock or structures.
Survey the Boundaries: Don’t rely on old fences or «handshake» agreements with neighbors. A professional survey is the only way to ensure you are actually buying the acreage you think you are.
Choosing a lender is not a one-size-fits-all endeavor. If you are an investor needing to move on a property immediately, a hard money lender like Lendersa might be your best bet, even if the cost is higher. If you are a long-term resident looking for stability, a traditional bank or a USDA program might be more appropriate.
One common mistake is failing to account for the «hidden» costs of land. Unlike a house, land often requires immediate investment in road access, water, and electricity. Always ensure your loan amount leaves room for these essential infrastructure upgrades. If you use your entire budget to buy the dirt, you may find yourself owning a beautiful view that you cannot actually reach or inhabit.
Always remember to check the impact of your inquiry. Utilizing lenders like JetzLoan or Acorn Finance that offer no-impact rate checks can save your credit score from unnecessary dents. Knowledge is power, and in the world of land lending, information is your best tool for success. Take your time, do your homework, and ensure your financing matches your long-term vision for the land.
Top 5 Lenders for Bad Credit Loans in North Carolina: 2026 Rankings
Last updated: 2026-10-16
Trying to balance your books in North Carolina can feel like trekking through a dense swamp when your credit score isn’t exactly stellar. Many residents find themselves facing unexpected car repairs, like a sudden transmission failure in Raleigh, or urgent medical bills from a trip to an urgent care center in Charlotte. These unexpected costs require immediate cash to keep life moving forward without a hitch.
These financial shocks can derail a monthly budget in a single afternoon. Suddenly, families find themselves scrambling to cover essential costs like rent or electricity. It is a stressful position to be in when the money you set aside for groceries is suddenly needed for a utility bill.
Finding the right lender involves more than just glancing at the interest rate. You have to weigh speed and accessibility against the total cost of borrowing. A loan with a lower interest rate might seem attractive on paper, but if it takes ten business days to fund, it won’t help you if the power company is threatening to shut off your electricity tomorrow.
On the flip side, a «quick cash» option might provide the speed you need, but it could carry an APR that makes the total repayment much higher than you expected. This list clarifies which options might suit your specific situation during uncertain times. It helps you weigh the trade-offs between immediate liquidity and long-term affordability.
FastLendGo
Addition Financial
PaydayPact
Credit Human
LoanStart
Evaluating Financial Assistance Across the Tar Heel State
The selection process for this ranking focused on how easily a borrower can secure funds when their credit history is less than perfect. We looked at the ease of the application process and the speed of funding. We also considered the flexibility offered to those with subprime scores.
We specifically scrutinized the user experience for ease of use. We noted whether applications could be completed on a smartphone while waiting in line at a clinic, or if they required a desktop computer and a pile of scanned documents. Convenience often dictates whether a lender is actually helpful in a crisis.
In North Carolina, high interest rates are a common side effect of easy approval. Because the risk to the lender is higher when a borrower has a low credit score, the price of that risk is reflected in the APR. Therefore, the ranking prioritizes lenders that provide clear pathways for those who might have been turned away by traditional big-box banks earlier in the week.
We looked for transparency in every option. We wanted to know: does the lender show the total repayment amount upfront, or do you only find out after you have signed the digital agreement? Knowing the final number before you commit is essential for anyone trying to manage a tight budget.
Lender Name
Loan Amounts
Credit Requirements
Funding Speed
Terms
FastLendGo
$500 – $5,000
Bad Credit / Fair Credit
Same day or next business day
see site
Addition Financial
see site
see site
see site
see site
PaydayPact
see site
Guaranteed approval online
see site
see site
Credit Human
As little as $500
No credit review
see site
Up to 72 months
LoanStart
Up to $40,000
see site
see site
see site
Ranking the Best Options for North Carolina Borrowers
1. FastLendGo
FastLendGo works well for those needing quick cash to cover immediate emergencies. Whether it is a sudden dental bill or a necessary auto repair, this service focuses on getting money into your hands without the usual mountain of paperwork. The streamlined digital interface is built for the modern consumer who needs to solve a problem in minutes rather than days. (fastlendgo.com)
This option is particularly suited for individuals who need specific amounts. You might need a $500 loan for a grocery bill gap or a $2,000 personal loan to fix a leaking roof. It caters to a wide spectrum of credit profiles, from those with bad credit due to a recent medical emergency to those with fair credit looking to build a better financial standing through consistent on-time repayments.
Pros:
Offers various loan sizes from $500 to $5,000.
Fast funding, potentially arriving the same day.
No minimum credit score required to qualify.
Cons:
Limited to specific smaller loan amounts.
2. Addition Financial
Addition Financial focuses on comprehensive banking needs beyond just quick cash injections. They offer a suite of products including checking accounts, credit cards, and mortgages. This makes them a more traditional choice for those looking to build a long-term relationship with a financial institution rather than just finding a one-off solution.
For members looking to grow their assets, they provide savings options and competitive rates. It is a solid choice if you want a stable institution rather than just a quick fix for an immediate financial crisis. If your goal is to move away from the high-interest cycle and toward traditional banking, this is a logical step.
Pros:
Diverse range of banking products.
Potential for earning through referrals.
Comprehensive financial services.
Cons:
May require more extensive documentation than quick-cash lenders.
3. PaydayPact
PaydayPact acts as a highly accessible digital portal for those facing rejection elsewhere. Their online system is designed to be secure and user-friendly. You can apply from any device, whether you are on a phone while commuting on a bus in Durham or on a laptop at home. This accessibility is crucial for people who may not have a fixed desk or a printer for paperwork.
The primary draw here is the promise of guaranteed approval online. This is a lifeline for someone who needs certainty in a moment of financial chaos. When you are facing a late fee on a rent payment, knowing you will get a «yes» or «no» immediately can significantly reduce the psychological stress of the situation.
Pros:
High accessibility via mobile devices.
Secure online application process.
Focused on guaranteed approval.
Cons:
High interest rates are common with this type of model.
4. Credit Human
Credit Human offers a more structured approach to borrowing with fixed rates. They provide a safety net for those who need to borrow as little as $500, but want the stability of a set repayment schedule. Because the rates are fixed, you won’t have to worry about your monthly payment changing unexpectedly due to market fluctuations.
One of their standout features is the ability to borrow without a traditional credit review. This makes them a very strong contender for anyone in North Carolina who is tired of being judged solely by a three-digit number on a screen. They may look at your broader financial stability, making them an excellent option for those who have had a temporary setback but are otherwise reliable.
Pros:
Flexible repayment options up to 72 months.
No credit review required for some products.
Fixed rates provide predictability.
Cons:
Terms can be long, leading to more total interest paid.
5. LoanStart
LoanStart functions as a matching service that connects borrowers with a network of affiliate lenders. Instead of looking at one single bucket of money, you are looking at a wide net of potential partners that might fit your specific needs. This is helpful because «one size does not fit all» in the lending world; what works for a student might not work for a small business owner.
This is the heavy hitter for those who need larger sums, with the potential to access up to $40,000. It is a great option for those who have maxed out credit cards and need a larger, structured installment loan to consolidate debt. By rolling several high-interest credit card balances into one larger loan, you can simplify your monthly finances and potentially save hundreds of dollars in interest over time.
Pros:
Potential for high loan amounts up to $40,000.
Free service that does not affect your credit score.
Connects you to a wide network of partners.
Cons:
You are at the mercy of the affiliate lender’s specific terms.
Comparing Loan Types: Quick Cash vs. Installment Loans
Understanding the difference between loan types is vital for North Carolina residents trying to manage their debt. Most lenders fall into one of two categories: Short-term/High-interest or Long-term/Installment loans. Choosing the wrong one can lead to a cycle of borrowing that is difficult to break.
Feature
Short-Term Loans
Installment Loans
Typical Duration
Days to a few months
12 to 72 months
Interest Rates
Very High (Often 300%+)
Moderate to High (10% – 36%)
Best Use Case
Immediate emergencies (e.g., a $200 utility bill)
Debt consolidation or large repairs (e.g., a $3,000 car engine)
Repayment Structure
Lump sum or frequent small payments
Fixed monthly installments
If you are facing a one-time expense that will be cleared by your next paycheck, a short-term loan might be the fastest path. However, if the amount you need is larger than your next two paychecks combined, an installment loan is a much safer way to avoid a «debt trap.»
Strategies for Managing Debt After Borrowing
Securing funds is only the first step; the second, and often more difficult, step is managing the repayment. Many North Carolina residents find themselves in a position where they have successfully resolved their immediate crisis but are now burdened by the new loan. To avoid this, consider these three proactive steps:
Automate Your Payments: Set up automatic transfers from your checking account to the lender the day after you receive your paycheck. This ensures you never miss a payment, which is crucial for protecting your credit score.
Prioritize High-Interest Debt: If you have multiple loans, use the «avalanche method.» This involves paying the minimum on all loans but putting every extra dollar toward the loan with the highest interest rate first. This mathematically minimizes the total amount of interest you pay over time.
Negotiate with Creditors: If you are borrowing because you cannot pay a medical bill or a utility bill, call the provider *before* you take out a loan. Many companies have hardship programs or can offer a payment plan that is much cheaper than the interest rate on a quick-cash loan.
Avoiding Common Pitfalls When Borrowing
When you are in a pinch, it is easy to sign a contract without reading the fine print. Always look for the «total cost of credit,» which tells you exactly how much you will have paid back by the end of the loan term. For example, a $1,000 loan with a high interest rate might require you to pay back $1,500 over six months. That $500 difference is the «cost» of the convenience.
Avoid the trap of taking out a loan just to pay off another high-interest debt unless the new loan has a significantly lower rate. If you are using a high-interest payday loan to pay off a credit card, you are effectively moving the debt from one expensive bucket to an even more expensive one. If you find yourself constantly cycling through short-term loans, you might be stuck in a debt spiral that is hard to escape. This is often a sign that the underlying budget needs restructuring rather than more credit.
Lastly, verify the legitimacy of the lender before providing any sensitive information. While the digital age makes borrowing easy, it also makes it simple for bad actors to mimic real companies. Scammers often use aggressive language, like «You have been pre-approved! Act now or lose the offer!» to pressure you into giving up your Social Security number or bank login details. Always use official, secure websites to protect your identity and your wallet. Look for the «https://» in the URL and ensure the site has a padlock icon in the address bar before entering any personal data.
Top 6 Lenders for Loans for Postal Employees with Bad Credit in 2026
Last updated: 2026-10-17
Managing money while working long, exhausting shifts at the post office can feel like trekking through deep snow. Life often throws a curveball that a standard paycheck cannot catch in time. For many postal workers, a sudden car repair or an unexpected medical bill requires cash that traditional banks often refuse to provide quickly.
When you are balancing the physical toll of a mail route with the mental strain of household expenses, a financial hurdle can feel impossible to clear. If your credit score takes a dip, the path to funding becomes a winding road. It is not just about finding any money; it is about finding a partner that understands the stability of government employment.
A traditional bank might see a temporary drop in your FICO score as a reason to deny you. Specialized lenders, however, recognize the long-term reliability of a federal paycheck. This ranking looks at how different lenders treat those who need a hand up, focusing on accessibility, speed, and how much they actually understand your situation.
USPS Federal Credit Union
Federal Employee Loans
JetzLoan
BMG Money
Acorn Finance
Credit Ninja
How These Lenders Were Evaluated
Finding a reliable source of capital requires looking past the shiny advertisements and «instant approval» banners online. This evaluation focused on how well each lender accommodates the specific reality of postal employees. We looked at whether they require a high FICO score or if they prioritize the stability of a federal paycheck through methods like payroll allotments.
For a postal worker, proving income through a steady, government-backed salary is often more important than a perfect credit history. We prioritized lenders that recognize this distinction. We also weighed speed against cost. A lender that provides funds in twenty-four hours is a lifesaver for an emergency, like a transmission failure on a delivery vehicle.
However, the interest rate determines if that lifesaver becomes a heavy weight later. We scrutinized loan amounts, repayment flexibility, and whether the application process would ding a credit score before a decision is even made. We specifically looked for «soft pull» options—processes that allow you to see your potential rate without the permanent damage of a «hard inquiry.»
Lender Name
Loan Amounts
Terms
Funding Speed
Credit Requirements
USPS Federal Credit Union
Up to $15,000
See site
See site
See site
Federal Employee Loans
$500 – $3,000
6 – 12 months
Same-day
No FICO check
JetzLoan
Up to $35,000
See site
Within 24 hours
No hard pull
BMG Money
$500 – $12,000
6 – 48 months
Instant availability
Regardless of score
Acorn Finance
See site
See site
See site
No score impact
Credit Ninja
See site
See site
Same day decision
See site
Ranking of Best Lenders for Postal Workers
1. USPS Federal Credit Union
Serving the community since 1934, this institution is built on the idea of «people helping people.» For a postal employee, there is a certain comfort in working with a credit union that shares your professional roots. They offer a sense of belonging that a massive, faceless national bank simply cannot replicate.
Because credit unions are member-owned nonprofits, their primary goal is to serve their members rather than maximize profits for distant shareholders. They provide various options, including personal loans that can reach up to $15,000. These are designed to help with life’s milestones or unexpected hurdles, such as consolidating high-interest credit card debt or covering a sudden move.
Because they understand the nuances of federal employment—including how pay raises and seniority-based adjustments work—their products often feel tailored to the specific lifestyle of a dedicated postal worker. When you speak with them, you aren’t just an account number; you are part of the institution’s history.
Pros:
Tailored specifically for USPS employees
Personal loans up to $15,000
Flexible terms for various life needs
Cons:
May require membership or specific eligibility
2. Federal Employee Loans
Sometimes, you don’t need a massive windfall; you just need a bridge to get you to the next payday. This lender specializes in allotment loans, which are designed specifically for the government and USPS workforce. An allotment is a way to have a portion of your paycheck automatically diverted to repay a loan.
This provides a level of security to the lender that allows them to offer much more lenient terms to the borrower. This is a straightforward approach for those who need a quick fix without the headache of traditional underwriting. The beauty of this service lies in its simplicity.
They do not care about your FICO score, focusing instead on your status as a federal worker and your ability to demonstrate a steady stream of income through your pay stubs. If you need a small amount to keep the lights on or keep the tank full, this is a direct and efficient route. It is the digital equivalent of a small, helpful nod from a colleague on the loading dock.
Pros:
No FICO credit check required
Same-day funding for quick relief
Small, manageable loan amounts
Cons:
Lower maximum loan amounts compared to others
3. JetzLoan
In a world where everything moves at the speed of a fiber-optic connection, waiting weeks for a loan is a relic of the past. JetzLoan focuses heavily on velocity, aiming to get funds into your account within a single day. It is built for the person who needs cash yesterday—perhaps because an appliance broke or an urgent repair is required.
They act as a bridge, connecting you with various lenders so you can compare options without the fear of a credit score penalty. This marketplace model is highly advantageous. Instead of you applying to ten different banks and receiving ten different «hard pulls» on your credit report, JetzLoan allows you to see what you qualify for with a single inquiry.
It is a modern solution for those who want to see their options clearly without playing a dangerous game of «guess the interest rate.» You get to see the reality of your options without the stress of multiple applications.
Pros:
Funds can arrive in as little as 24 hours
No hard credit pull during the inquiry
High maximum loan limit of $35,000
Cons:
Acts as a marketplace rather than a direct lender
4. BMG Money
Life is about more than just a number on a credit report. BMG Money operates on the philosophy that your potential isn’t defined by a score. They cater specifically to employees and retirees who are working toward a better financial future but need assistance right now. They recognize that a credit score is a snapshot of the past, whereas your current employment and future earnings are much better indicators of your reliability.
Their loans are versatile, ranging from $500 all the way up to $12,000. This range makes them useful for everything from minor repairs to more significant debt consolidation efforts. For example, instead of paying 25% interest on several different store credit cards, you could use a BMG Money loan to combine those debts into one single monthly payment.
They aim to be a partner in your financial wellness journey, offering a path toward stability. It is a practical way to clean up your finances with a more manageable interest rate and a single monthly deadline.
Pros:
Available regardless of credit score
Instant funding options available
Flexible terms up to 48 months
Cons:
Interest rates can be higher for some borrowers
5. Acorn Finance
If your financial need is tied specifically to improving your home, Acorn Finance is a specialist in that niche. They focus on contractor financing, making it easier to fund home improvement projects even if your credit isn’t pristine. This is particularly useful for postal workers who may have spent years investing in their community and are now looking to invest in their own property’s value.
They pride themselves on a transparent process where you can check rates without impacting your credit. It is an excellent way to see what is possible for a kitchen remodel, a new roof, or a new deck without the stress of a formal application. By streamlining the connection between the homeowner and the contractor-focused lender, they remove much of the friction typically found in home improvement financing.
Pros:
Zero dealer fees for contractors
No credit score impact when checking rates
Excellent customer reviews on Trustpilot
Cons:
Primarily focused on home improvement projects
6. Credit Ninja
When traditional banks slam the door shut, Credit Ninja is often the one standing in the hallway with an open one. They specialize in helping those who might not qualify for standard personal loans, such as individuals with recent credit hiccups or those with a limited credit history. Their application process is designed to be quick, simple, and incredibly fast.
They remove the bureaucratic red tape that often stops small loans in their tracks. The goal here is to provide a solution for life’s unexpected expenses when you feel like you’ve run out of options. If you can’t find a «yes» elsewhere due to a specific credit issue, their installment loans might provide the breathing room you require.
It is a safety net for those navigating the more turbulent waters of the credit system. They offer a way forward when other doors seem permanently locked.
Pros:
Fast, same-day decisions
Simple and quick online application
Designed for those with non-traditional credit
Cons:
May not be suitable for all credit situations
Common Pitfalls to Avoid When Borrowing
Before you sign your name on a loan agreement, it is vital to understand the mechanics of what you are agreeing to. Many borrowers fall victim to «teaser rates» or misleading marketing that highlights a low monthly payment while burying the total cost of the loan in the fine print. To avoid these traps, always ask for a «Total Cost of Loan» breakdown.
This figure tells you exactly how much cash will leave your pocket from the first payment to the very last one. Consider these three specific areas of caution:
The Prepayment Penalty: Some lenders charge a fee if you try to pay the loan off early. If you receive a bonus or a tax refund and want to clear your debt, you shouldn’t be punished for being responsible. Always look for loans with «no prepayment penalties.»
The Origination Fee: This is a fee charged by the lender for processing the loan, often taken directly from the funds you receive. If you need exactly $2,000 for a repair, a lender with a 5% origination fee will only send you $1,900. Always verify the «net proceeds» you will receive.
Variable vs. Fixed Rates: A variable rate might start low, but if the economy shifts, your monthly payment could climb significantly. For a fixed monthly budget, a fixed-rate loan is almost always the safer, more predictable choice.
How to Prepare Your Application for Success
Even when working with lenders who are flexible on credit scores, being prepared can significantly increase your chances of approval and help you secure a better rate. Lenders want to see that you are organized and that your income is verifiable. Taking thirty minutes to gather your paperwork beforehand can prevent a delay that could leave you without funds when you need them most.
Follow these steps to streamline your application process:
Gather Proof of Income: Have your most recent two or three pay stubs ready. For USPS employees, having your most recent W-2 handy is also helpful for confirming your annual earnings and employment duration.
Verify Your Expenses: A lender will look at your «debt-to-income ratio.» This is the amount of your monthly income that goes toward paying off existing debts. Knowing your monthly totals for rent, car payments, and other loans will help you estimate what you can realistically afford.
Check Your Details: Ensure your address, employer information, and contact details match your official documents exactly. Discrepancies between your application and your bank records can trigger automatic fraud flags, causing unnecessary delays.
Review Your Credit Report: Even if you are applying for a «no credit check» loan, it is wise to know what is on your report. If there is an error—such as an incorrect late payment—correcting it now can help you qualify for better terms with other lenders in the future.
Choosing a lender is a bit like choosing a pair of work boots. You need something that fits your specific situation, provides the right amount of support, and won’t fall apart when things get heavy. The most important thing is to look at the total cost of borrowing, not just the monthly payment.
Avoid the trap of only looking at the «easy» part of the application. A lender that says «no credit check» is a lifesaver today, but the interest rates can be quite steep. Always calculate the total amount you will have paid back by the end of the term. It is better to know the truth upfront than to be surprised by a mountain of interest later.
Finally, remember that your employment status is a powerful tool. Many lenders view postal workers as reliable because of the stability of the job. Don’t be afraid to mention your professional background or look for lenders that specifically cater to federal employees, as this can often unlock better terms and more favorable views of your ability to repay.
Shopping Basket
Sur les plateformes de jeux en ligne agréées, les joueurs francophones profitent régulièrement d'offres promotionnelles pensées pour enrichir l'expérience dès l'inscription. Les bonus de bienvenue, les tours gratuits et les programmes de fidélité attirent un public varié, du débutant au parieur aguerri. Pour bien comparer les opérateurs, il est utile de consulter un comparatif sérieux qui détaille les conditions de mise, les jeux éligibles et le plafond des retraits. Beaucoup d'utilisateurs cherchent ainsi un Betify bonus attractif pour démarrer sur une nouvelle interface, et Betify bonus figure souvent parmi les références citées. L'Autorité Nationale des Jeux reste vigilante face aux dérives, ce qui rassure les amateurs soucieux de jouer dans un cadre légal et encadré, où la lutte contre l'addiction demeure une priorité constante.
Les amateurs de casino en ligne cherchent souvent des plateformes fiables qui proposent des bonus attractifs dès l'inscription, et c'est justement ce que certains opérateurs mettent en avant pour fidéliser les nouveaux joueurs francophones. Avant de valider un compte, il reste prudent de comparer les conditions de mise, la variété des jeux de table et la qualité du service client, car une offre alléchante peut cacher des exigences élevées en matière de retrait. Parmi les bonus actuellement évoqués par la communauté, le Betify bonus circule régulièrement sur les forums spécialisés, accompagné de retours d'expérience sur les machines à sous, le live casino et les paris sportifs. Les joueurs seasoned apprécient particulièrement la transparence des cotes et la rapidité des transactions, deux critères devenus incontournables dans l'univers compétitif de l'iGaming européen.
Avant de s'inscrire sur une plateforme de jeux d'argent en ligne, il est essentiel de comparer les offres de bonus de bienvenue, la diversité des machines à sous et la qualité du service client. Les joueurs francophones recherchent souvent un site qui combine une ludothèque riche, des retraits rapides en euros et une licence reconnue. Pour se faire un avis éclairé sur l'une des plateformes les plus discutées du moment, beaucoup consultent un MyStake avis détaillé qui passe en revue les conditions de mise, le cashback hebdomadaire et les tournois de live casino proposés aux membres inscrits.
Les amateurs de jeux d'argent en ligne recherchent souvent des plateformes fiables offrant une large sélection de machines à sous, de jeux de table et de paris sportifs, et plusieurs comparatifs francophones recommandent MyStake casino pour la diversité de son catalogue et la qualité de son service client francophone.
Pour les joueurs francophones qui comparent les opérateurs de paris en ligne, Aruba Bet figure régulièrement parmi les options discutées sur les forums spécialisés, notamment grâce à sa couverture des ligues européennes et à ses bonus de bienvenue modulables selon le profil du parieur.
Sur les forums de joueurs francophones, on discute souvent des meilleures plateformes pour profiter des machines à sous, du blackjack en direct et des tournois de poker en ligne, et plusieurs membres recommandent Celsius Casino pour la fluidité de son interface mobile et la rapidité de ses retraits.
Les passionnés de jeux d'argent en ligne recherchent régulièrement des plateformes sérieuses offrant des conditions intéressantes et une ludothèque complète. Dans l'univers francophone des casinos virtuels, certains opérateurs se distinguent par leurs promotions généreuses, leur service client réactif et leur compatibilité avec les appareils mobiles. Pour profiter d'une offre spécialement pensée pour les nouveaux inscrits, il est pertinent de découvrir le Celsius Casino bonus qui propose un accompagnement adapté aux joueurs débutants comme aux habitués des tables en direct et des machines à sous modernes.
Les amateurs de jeux d'argent en ligne cherchent souvent des retours fiables avant de s'inscrire sur une nouvelle plateforme, et le Unique Casino avis offre un panorama détaillé des bonus, de la ludothèque et de la réactivité du service client pour les joueurs francophones.
Les amateurs de jeux d'argent en France cherchent souvent une plateforme fiable pour profiter des machines à sous, du blackjack et de la roulette depuis chez eux. Avant de s'inscrire, il est prudent de comparer les bonus de bienvenue, la qualité du service client et la diversité des éditeurs proposés. Pour découvrir une sélection variée de tables en direct et de titres exclusifs, rendez-vous sur Unique Casino en ligne, un site qui réunit plusieurs références du secteur francophone avec des conditions de jeu transparentes et des retraits rapides.
Les joueurs francophones à la recherche d'une plateforme de casino en ligne fiable accordent souvent de l'importance à la diversité des machines à sous, à la présence de jeux de table classiques comme la roulette et le blackjack, ainsi qu'à la qualité du service client. Avant de s'inscrire, beaucoup consultent des comparatifs sérieux qui recensent les opérateurs agréés par l'ANJ et analysent les conditions des offres de bienvenue. Certains établissements proposent également des programmes de fidélité permettant de cumuler des points échangeables contre des tours gratuits ou des crédits de jeu. Pour profiter d'un démarrage avantageux, il est pertinent de vérifier les promotions en cours, comme le Wild Sultan bonus, qui figure parmi les offres les plus généreuses du marché francophone.
When players weigh the perks of weekly reload bonuses against the appeal of cashback deals, the small print on wagering requirements often tips the balance. Live dealer studios have tightened their table limits lately, and a handful of crypto-friendly brands now settle withdrawals within minutes rather than hours. For anyone keeping tabs on the latest sign-up flows, a quick stake login walkthrough can save a few frustrating minutes during the first deposit. Loyalty tiers are also getting more transparent, with clearer point-to-cash conversion rates showing up across newer platforms.
Reviewing the latest online casino platforms, players often weigh welcome bonus size, slot RTP ranges, and live dealer quality before committing, yet few check how quickly the site handles the stake login step when a session expires mid-spin. Reliable authentication keeps the reels rolling without forcing a full reload of the lobby.
Players looking for a smooth start often check the mystake login page first to handle their account entry without delays. Many UK bettors appreciate a clean dashboard where game libraries, deposit options, and bonus trackers sit side by side, and a reliable sign-in flow keeps the session uninterrupted from the very first spin on a roulette wheel.
Seasoned players often weigh volatility ratings when comparing slot libraries, and platforms like Westace Casino tend to publish return-to-player percentages alongside each title, which makes it easier to spot games that suit a conservative bankroll strategy before committing real money to the reels.
Wie graag een avondje online gokplezier zoekt, komt al snel uit bij platforms zoals Spinboss, waar een breed spelaanbod met populaire gokkasten, live tafels en sportweddenschappen op je wacht. Veel spelers letten bij het kiezen van een casino op zaken als een geldige vergunning, eerlijke uitbetalingspercentages en snelle stortingen via iDEAL of een andere vertrouwde betaalmethode. Daarnaast speelt de gebruikservaring een grote rol: een overzichtelijke lobby, soepele navigatie en aantrekkelijke bonussen voor zowel nieuwe als terugkerende leden maken het verschil. Wie zich eerst wil oriënteren, kan via recensies en forums ervaringen van andere Nederlandse spelers nalezen, zodat je met een gerust gevoel een weloverwogen keuze maakt voor een betrouwbare en plezierige speelomgeving.
Mittlerweile tummeln sich unzählige Online-Casinos auf dem deutschen Markt, und die Auswahl fällt selbst geübten Spielern nicht leicht. Wichtig sind vor allem eine gültige Lizenz, faire Auszahlungsquoten und ein zuverlässiger Kundendienst, der auch auf Deutsch erreichbar ist. Wer diese Kriterien anlegt, landet früher oder später bei Godz Casino Deutschland, einem Anbieter, der in unabhängigen Vergleichstests regelmäßig gut abschneidet.
Voor liefhebbers van online kansspelen is het vinden van een degelijk platform soms een hele zoektocht, zeker nu er maandelijks nieuwe aanbieders bijkomen. Spinboss Casino staat bij een flinke groep Nederlandse spelers bekend om het ruime spelaanbod, de overzichtelijke indeling van de lobby en de vlotte verwerking van uitbetalingen. Daarnaast valt op dat de welkomstbonus eerlijk oogt en dat de inzetvoorwaarden duidelijk op de site worden toegelicht. Wie graag tussen de bedrijven door een rondje speelt, merkt al snel dat de laadtijden van de spellen prettig kort blijven, terwijl de klantenservice via live chat doorgaans binnen enkele minuten reageert. Nieuwe spelers kunnen zich in een paar stappen registreren, waarna het speelgeld direct beschikbaar is en de eerste storting met iDEAL of een andere bekende betaalmethode kan worden voldaan.
Beim Stöbern durch Online-Casinos achten erfahrene Spieler besonders auf die Auswahl an Spielautomaten, Live-Dealer-Tischen und progressiven Jackpots. Ein seriöser Anbieter überzeugt nicht nur durch eine breite Palette an Titeln, sondern auch durch faire Umsatzbedingungen und einen kompetenten Kundenservice, der rund um die Uhr erreichbar ist. Wer sich vor der Registrierung genauer informieren möchte, findet auf Godz hilfreiche Vergleichsmöglichkeiten und aktuelle Erfahrungsberichte aus der Branche.
De wereld van online casino's blijft zich razendsnel ontwikkelen, en steeds meer Nederlandse spelers ontdekken het gemak van digitaal gokken vanuit huis. Of je nu graag aan de slag gaat met klassieke tafelspellen zoals blackjack en roulette, of liever geniet van de spanning van moderne videoslots met progressieve jackpots, het aanbod is tegenwoordig enorm gevarieerd. Live casino-ervaringen met professionele dealers brengen de sfeer van een echte speelvloer rechtstreeks naar je scherm, inclusief interactie en realtime spelverloop. Voor spelers die waarde hechten aan een betrouwbaar platform met een uitgebreid spelaanbod, snelle uitbetalingen en aantrekkelijke welkomstbonussen, is Spin Boss Casino een aanrader die zowel beginners als ervaren gokkers aanspreekt. Vergeet niet om altijd verantwoord te spelen en vooraf de voorwaarden van bonussen en promoties goed door te nemen, zodat je met een gerust hart kunt genieten van je favoriete casinospellen.
UK punters weighing live dealer tables against crypto-friendly slots often compare reload bonuses, wagering weights, and withdrawal turnaround times before committing a bankroll, and a fresh review of Kingdom casino walks through how its welcome package stacks up against rival sites on the British market this season.
Players comparing online casino options for Wino casino can review Wino casino as a focused destination for the topic.
Wielu polskich graczy szuka dziś wygodnych metod zasilania konta, dlatego coraz częściej sprawdzane są recenzje kasyna wplata BLIK w portalach z rankingami. Warto zwrócić uwagę na szybkość transakcji, limity wpłat oraz dostępność bonusów powitalnych dla nowych użytkowników. Przed rejestracją dobrze jest porównać ofertę kilku operatorów, sprawdzić licencję i opinie innych graczy na forach branżowych.
Polscy miłośnicy hazardu coraz chętniej wybierają gry w przeglądarce, pomijając tradycyjne lokale. Kluczowe znaczenie ma wygodna wpłata w złotówkach, szybka weryfikacja konta i dostęp do setek tytułów od znanych dostawców oprogramowania. Turnieje slotowe z pulą nagród oraz cotygodniowy cashback przyciągają zarówno nowicjuszy, jak i stałych bywalców. Przed rejestracją dobrze jest zapoznać się z opiniami graczy i rankingami portali branżowych, na przykład wskazującymi najlepsze kasyno online na rynku.
A seasoned slots fan weighing fresh welcome packages often compares payout percentages, bonus wagering rules, and live dealer depth before settling on a platform, and that same checklist led a few players toward Cazeus Casino UK when scanning operators that hold a valid UKGC licence and publish transparent RTP data for their catalog.
Online gokken blijft populair onder Nederlandse spelers die op zoek zijn naar een spannende avond met kans op mooie winsten. Bij het kiezen van een betrouwbaar casino letten veel mensen op de licentie, het spelaanbod en de klantenservice. Wie graag de nieuwste videoslots uitprobeert of live dealer tafels wil ervaren, doet er goed aan om vooraf de bonusvoorwaarden te vergelijken en te kijken naar de uitbetalingspercentages. Voor meer informatie over veilige stortingsmethoden en actuele promoties kun je terecht op https://schooldehofakker.nl/, waar je ook handige checklists vindt voor verantwoord spelgedrag.
Cotiza tu proyecto
¿Listo para comenzar tu proyecto?Conversemos
Déjanos tus datos en el siguiente formulario y muy pronto nos pondremos en contacto contigo
¡Hola! Bienvenido a nuestro sitio web 🌎 ¿Te interesa conversar con nosotros directamente? 🗨️
Abrir chat
Players comparing online casino options for NV casino can review NV casino as a focused destination for the topic.
Pri výbere online kasína na Slovensku hráčom záleží nielen na rozmanitosti hier, ale aj na férových podmienkach a spoľahlivých platobných metódach. Populárne platformy lákajú nových používateľov uvítacími bonusmi, pravidelnými turnajmi a vernostnými programami, ktoré spríjemňujú každodenné hranie. Ak hľadáte overenú značku so širokou ponukou automatov, rulety a živých hier, určite sa oplatí vyskúšať NV casino, ktoré si získalo dôveru mnohých slovenských hráčov.
V posledných rokoch zaznamenali online kasína na Slovensku výrazný nárast popularity, pretože hráči oceňujú pohodlie hrania z domova. Kvalitné platformy ponúkajú rozmanitý výber slotov, rulety aj blackjacku, pričom kladú dôraz na bezpečnosť a férovosť hier. Medzi overené prevádzky patrí NV casino, ktoré si získalo dôveru hráčov vďaka rýchlym transakciám a atraktívnym uvítacím bonusom pre nových aj verných zákazníkov.
Pri výbere online kasína je dôležité venovať pozornosť licenciám, bezpečnosti a rozmanitosti hier. NV casino patrí medzi platformy, ktoré kladú dôraz na zodpovedné hranie a zároveň ponúkajú štedré bonusy, rýchle výbery peňazí a nonstop zákaznícku podporu v slovenčine.
Players comparing online casino options for NV casino can review NV casino as a focused destination for the topic.
Mūsdienu tiešsaistes azartspēļu vidē spēlētāji arvien vairāk novērtē iespēju izbaudīt kazino spēles no mājām ērtā un drošā veidā. Daudzi Latvijas lietotāji izvēlas NV casino, jo šī platforma piedāvā plašu spēļu klāstu, ātras izmaksas un profesionālu klientu atbalstu. Populārākās izklaides iespējas ietver spēļu automātus, ruleti, blekdžeku un dzīvā dīlera kazino, kas nodrošina autentisku atmosfēru.
Mūsdienu tiešsaistes azartspēļu vidē spēlētāji arvien vairāk pievērš uzmanību licencēšanas nosacījumiem un izmaksu ātrumam, izvēloties platformu ilgtermiņa sadarbībai. Ja meklējat vietni ar plašu spēļu klāstu un caurspīdīgiem noteikumiem, NV casino piedāvā stabilu pieredzi ar ātru klientu atbalstu, dažādām akcijām jaunajiem dalībniekiem un iespēju izmēģināt gan klasiskās galda spēles, gan modernas video slotu mašīnas bez liekas sarežģītības.
Jucătorii din România apreciază platformele care oferă o experiență completă, iar NV casino reușește să combine bonusurile atractive cu o selecție variată de jocuri de noroc online, de la sloturi moderne la mese de ruletă cu dealeri live.
Jucătorii din România apreciază platformele de cazino online care combină o interfață prietenoasă cu promoții avantajoase și o selecție variată de jocuri. Printre operatorii activi pe piață se numără și NV casino, un brand care pune accent pe sloturi moderne, metode de plată sigure și asistență pentru clienți în limba română. Pentru o experiență lipsită de griji, este recomandat să alegi mereu un site deținător de licență ONJN, care garantează transparență și protecția datelor personale.
Jucătorii care compară opțiuni de cazinou online pentru NV casino pot consulta NV casino ca destinație de referință pentru subiect.
Svenska spelentusiaster som söker en modern plattform för nätcasino hittar ofta ett brett utbud av slots, livebord och snabba uttag hos https://lokken2805.com/, där fokus ligger på ansvarsfullt spelande, tydliga villkor och en smidig mobilupplevelse för både nybörjare och erfarna highrollers.
Många svenska spelare söker efter pålitliga casinon med generösa bonusar och ett varierat spelutbud, och det är därför intressant att se hur 30Bet Сasino har etablerat sig på marknaden. Operatören kombinerar klassiska slots med moderna live casino-upplevelser och riktar sig särskilt till den nordiska publiken genom lokala betalningsmetoder, snabba uttag och kundsupport som hanteras på svenska dygnet runt.
Många svenska spelare söker efter en pålitlig spelsajt med brett utbud av slots, live casino och sportbetting. 30Bet har seglat upp som ett omtyckt val tack vare snabba insättningar, generösa välkomstbonusar och en mobilvänlig plattform som fungerar smidigt även på äldre enheter.
Den svenska marknaden för onlinecasino fortsätter att växa, och plattformar som 30Bet Сasino erbjuder allt från klassiska spelautomater till moderna liveupplevelser med riktiga dealers i realtid.
Steeds meer Nederlandse spelers stappen over naar online casino's vanwege het ruime spelaanbod en de flexibele speelmogelijkheden. Wie op zoek is naar een laagdrempelige kennismaking zonder direct eigen geld in te leggen, kan terecht bij het Casoola Gratis Bonus initiatief, dat nieuwe accounts beloont met speeltegoed om verschillende gokkasten en tafelspellen uit te proberen. Controleer altijd de rondspeelvoorwaarden en de geldigheidsduur van de promotie voordat je een account aanmaakt.
Nederlandse spelers ontdekken steeds vaker de wereld van online gokken via moderne platforms waar je met iDEAL kunt storten en binnen enkele minuten aan tafel zit. Wie op zoek is naar een betrouwbaar overzicht van aanbieders, bonusvoorwaarden en spelaanbod, vergelijkt het liefst actuele reviews voordat er een account wordt aangemaakt. Een naam die daarbij regelmatig opduikt tussen de buitenlandse casino's zonder Cruks-registratie is SkyHills Casino, een platform dat zich richt op een brede selectie slots, live tafels en toernooien voor zowel beginnende als ervaren gokkers.
Regulars who jump between mobile and desktop often pin the Fortunica Login to their browser shortcuts so they can pick up a hand of live blackjack the moment they sit down, skipping past banners and bonus pop-ups entirely.
Wie in Nederland wil spelen in een online casino doet er verstandig aan om alleen te kiezen voor aanbieders met een vergunning van de Kansspelautoriteit, zodat stortingen en uitbetalingen veilig worden verwerkt. In de speelhal van een goed gereguleerde site staan doorgaans honderden gokkasten, tafelspellen en een live casino waar je met echte croupiers kunt gokken. Onder de populaire videoslots vallen titels als Foxy Gold, vaak gecombineerd met progressieve jackpots, free spins en toernooien voor trouwe spelers. Lees altijd de bonusvoorwaarden, stel een limiet in en speel alleen met geld dat je kunt missen, zodat het gokken een leuke vrijetijdsbesteding blijft.
Nederlandse gokliefhebbers vergelijken steeds vaker online casino's op spelaanbod, uitbetalingssnelheid en bonussen. Wie houdt van een afwisselend lobby met gokkasten, jackpot spellen en live tafels, kan bij Casoola rekenen op een overzichtelijke interface en storten via iDEAL. Nieuwe leden krijgen een welkomstpakket met gratis spins, terwijl trouwe spelers profiteren van wekelijkse promoties en een persoonlijke accountmanager. Voor wie eerst wil oefenen, biedt het platform demoversies van populaire titels, zodat je zonder risico het speeltempo kunt verkennen voordat je echt geld inzet.
Players comparing online casino options for GQBet can review GQBet as a focused destination for the topic.
Spelers die online casinoopties voor InstantCasino vergelijken, kunnen InstantCasino beschouwen als een geschikte bestemming voor dit onderwerp.
Suomessa turvallisen pelaamisen valinnassa kannattaa tarkistaa toimilupa ja vastuullisen pelaamisen työkalut ennen rekisteröitymistä, ja Titaani casino tarjoaa selkeät ohjeet sekä nopean asiakaspalvelun suomeksi vuorokauden ympäri.
Kun etsit uutta pelipaikkaa, kurkkaa myös Munkki Kasino, joka tarjoaa nopeat kotiutukset ja laajan kolikkopelivalikoiman suomalaisille pelaajille.
Många spelare upplever att smidig verifiering och tydliga insättningsgränser gör hela skillnaden, och det är just en sådan helhetskänsla man hittar hos Kumobet.
Suomalaisten kolikkopelien ystäville nopeat kotiutukset ovat usein ratkaiseva valintakriteeri, ja Bonusbet tarjoaa kilpailukykyisen vaihtoehdon.
Ukentlige turneringer med leaderboard-premier er en favoritt blant norske casinospillere, og hos Betpanda finner du både spilleautomat-kamper og live roulette-konkurranser med cashback-belønninger for VIP-medlemmer som liker å konkurrere gjennom hele måneden.
Wondering if weekend reload offers are worth claiming? Before you commit, browse the Fortunica welcome package and weekly cashback details to see whether the terms suit your play style.
When weighing welcome bonuses, payout speed, and licensing credibility across competing brands, JeetCity consistently shows up on shortlists for English-speaking players.
Wie herkent het niet: je wilt snel een account aanmaken zonder gedoe met DigiD of iDIN, gewoon met e-mail en een paar klikken. Bij de beste casino zonder iDIN ervaar je hoe soepel registreren kan voelen, inclusief royale welkomstbonussen, ruime spelaanbod en vlotte uitbetalingen via iDEAL of crypto.
Sur les forums spécialisés, on note que beaucoup de francophones s'orientent désormais vers un casino en ligne sans vérification pour gagner du temps lors de l'inscription et profiter plus vite des machines à sous.
Always check the wagering requirements on any casino welcome bonus before depositing. Diversify your betting knowledge by learning about greyhound trainers to watch this season and other form-based strategies.
Always check the wagering requirements on any casino welcome bonus before depositing. Diversify your betting knowledge by learning about greyhound trainers to watch this season and other form-based strategies.
Live dealer tables now run 24/7 with side-bet multipliers, and a punter chasing early betting value on Arsenal before kickoff can fit a quick blackjack session in between fixtures.
When weighing mobile apps alongside cashier convenience, check whether LegionBet Casino matches the experience you're after before committing real funds.
When checking mobile compatibility, the app interface at Winner Casino loads quickly across devices and supports smooth navigation between slot and live dealer sections for new users testing wagering requirements on the go.
When you care more about a quick deposit limit setup than flashy banners, a streamlined cashier page matters. Stake Casino Stake Casino delivers that.